
May 2, 2010
property
New en bloc rules stricter but fairer
Proposed changes will cut time wastage and add more checks and balances
By Joyce Teo
Last week, the Government proposed changes to the Land Titles (Strata) Act, making the process of selling an estate enbloc stricter but also fairer than before. The changes are expected to take effect next month.
This came after the Ministry of Law received further feedback and suggestions on the Act. These range from requesting more procedural controls to loosening the regulations, as well as proposals to streamline and clarify the sale process.
The ministry had previously amended the Act in late 2007, when it introduced a raft of changes that made the process more transparent and regulated but also more complex and lengthy.
Here's a look at the changes this time round.
Role of the Strata Titles Board (STB)
Currently, STB both mediates and adjudicates on the objections filed by minority owners in en bloc sales.
But in recent years, some enbloc sale applications have become highly contentious, and have ended up in the High Court and even the Court of Appeal.
The proposed changes will reduce STB's role to only a mediatory one. This allows disputing parties to head straight for the courts without having to go through STB's adjudication process, thereby saving time and costs.
STB will be empowered to stop the mediation process if it is clear the parties are headed for the High Court.
'Any resolution at a mediation session is at the absolute discretion of the parties,' said the ministry.
'Any party that does not wish to proceed further with mediation may make known his intention to the STB and the STB shall decide if a stop order should be made.'
Another proposal stipulates that STB can spend no more than 60 continuous days mediating each case, to prevent undue delays and to give greater certainty to the mediation process.
STB can request any information or documents from any party related to the collective sale application, if deemed relevant, and order minority owners to share in the costs of the en bloc sale.
EGMs
Currently, extraordinary general meetings (EGMs) are required to elect a sale committee, appoint lawyers and consultants, and approve the apportionment method and the terms and conditions of the collective sale agreement.
During the sale process, EGMs are also required to be held to update owners on consent levels, sale proposals, bid amounts received, or the terms and conditions of the sale and purchase agreement.
One of the proposed changes will be to do away with those EGMs held to update owners as no decision-making is required.
Another change will enable an EGM to be dissolved if the quorum of 30 per cent (by share value of the development) is not reached within an hour of the start of the meeting.
If the quorum is not attained, the meeting will be considered a failed attempt.
This will address some concerns on lack of certainty when the sale committee convenes EGMs and owners are made to wait for an inordinate amount of time for the meeting to begin, said the ministry.
Failed attempts
There have been complaints about owners trying again and again to restart the en bloc sale process when previous attempts failed.
To discourage such repeated attempts when there is insufficient interest, a two-year restriction period will be imposed after a failed en bloc sale attempt.
This will give owners peace of mind and prevent the depletion of management corporation funds.
During these two years, the first retry to convene an EGM to reappoint a sale committee will require the agreement of 50 per cent by share value or of the total number of owners. This is up from the current level of 20 per cent by share value or 25 per cent of the total number of owners.
Any subsequent attempts to convene EGMs within this period will need 80 per cent by share value or the total number of owners. If there is another failed attempt, the stricter rules will apply for another two years.
A failed attempt occurs:
· If the quorum for an EGM convened to elect a sale committee is not met within an hour;
· When a resolution to elect the committee at an EGM is not passed;
· When the sale committee is dissolved or terminated; or
· When the collective sale agreement expires.
Sale committees
Currently, sale committee members have to disclose their interest in any property developer, property consultant, marketing agent or legal firm.
With the proposed amendments, sale committee members will also need to declare the extent of ownership that they or a connected person - either an immediate family member or a firm in which they have at least 5 per cent voting power - has in the development and when the purchase was made.
The additional disclosure requirements will allow owners to make a more informed choice on whom they want to elect into their sale committee.
Also, a sale committee member who does not consent to the sale can now be voted out by the other committee members by a simple majority when an application has been made to STB.
A sale committee will have one year to obtain the first signature for the collective sale agreement, failing which it will be dissolved automatically.
joyceteo@sph.com.sg

Monday, May 3, 2010
ST : No permit, no display ad
May 2, 2010
No permit, no display ad
By Melissa Pang

Housing agent Fabien Tan replaced a 4m by 2m banner ad with this smaller one after he was told the huge one was illegal. The BCA rules state that all outdoor ads - regardless of size - must have a licence. -- ST PHOTO: WONG KWAI CHOW
You could not have missed it if you had been walking or driving near the Lorong Chuan area last month.
A huge 4m by 2m banner advertising a home sale was draped over the fence at the back of a semi-detached house in Li Hwan estate.
It read 'For Sale Semi-detached $2.6 million' and gave the telephone number of the housing agent.
But the canvas display has since been taken down - and replaced with a much smaller one - because it broke the rules.
The banner was put up by housing agent Fabien Tan, 28, who felt that traditional publicity methods such as newspaper and online ads and fliers were either too expensive or took too much time to distribute.
So he spent $200 for the giant banner and placed it at the back of the house because it faces a busy traffic junction between Lorong Chuan and Ang Mo Kio Avenue 1.
But about a week after the banner went up, he was told by the Land Transport Authority to take it down as it was illegal and posed a danger to motorists.
He was also told that he would be fined if it was not removed.
Under Building and Construction Authority (BCA) rules, all forms of outdoor advertisements - regardless of size and where they are placed - must have a licence.
Outdoor advertisements are defined as 'outdoor display of any logo, symbol, sign, notice or other visual device, promoting any goods or services, brands of products or events'.
The rule applies even if the sign is placed within one's property.
The reason, said a BCA spokesman, is 'to ensure that such displays are mounted safely and befit the amenities of the place'.
Anyone who flouts the rules can be fined up to $5,000.
The cost of a display advertisement permit depends on its size. It is about $20 for displays not more than 1 sq m, and $140 for those between 5 sq m and 10 sq m.
Still, Mr Tan considers the $200 well-spent even though the banner was up for only about three weeks and the house remains unsold.
'I got more calls than usual from putting up the banner. But there were nuisance calls too,' he said.
BCA said that in the last year alone, it has compounded about 670 offences of unlicensed display of outdoor advertisement signs and signboards. These were put up by owners of properties, advertisers or advertising companies. There were 260 offences in 2008.
To curb the growing problem of unlicensed display advertisements, BCA conducts regular enforcement checks.
It also relies on feedback from the public and other relevant authorities.
Most residents in the Li Hwan estate interviewed said they were surprised when they saw the original banner.
Engineer Esmond Chua, 31, said: 'The first thing I thought was, 'Wow! It's very huge.' I was quite shocked when I saw it and thought it was quite distracting.'
But others did not mind.
Student Dylan Teoh, 18, thinks such banners are acceptable 'as long as it does not encroach on other people's space'.
--------------------------------------------------------------------------------
It pays to drive home a point
By Ng Hui Ying

More people, such as Mr Edwin Kheng from HSR Property Group, are using their cars to carry advertisements for themselves and other companies. The traffic police say those who wish to do so must first apply for a permit. -- ST PHOTO: KEVIN LIM
You must have seen those cars carrying advertisements for property agents or food companies.
But not many know that car owners can actually sell space on their vehicles for such promotional purposes.
Mr Johnson Soh, 42, manager of decal company Soh Guan Chuan Auto Supply, said more than 10 companies have approached him to find willing car owners. The carrot? Some firms foot the road tax for the owner's car - between $1,000 and $1,500 a year for a 1,600cc car - while others hand out petrol vouchers worth $500 to $1,000.
The companies are in fields ranging from liquor to health products and frozen food.
GenConcept, another decal company, said it has seen 50 per cent more enquiries over the past few years concerning advertising on both cars and commercial vehicles.
Renvertising, a company that specialises in advertising on wheels, also helps companies find car owners.
Renvertising's owner, Mr Jeff Peh, 26, said the number of private car owners who have signed on has grown from 220 in 2008 to about 500 now.
One such owner, who wanted to be known only as L. H., said the advertisement his car carries for 3A Car Mats has prompted many of his neighbours to buy the product.
The 33-year-old car dealer, who drives a Proton Wira, is paid $150 a month for his help. That is enough to cover his road tax of $600 and insurance of about $1,000 yearly.
Sometimes, the advertiser works out a win-win deal with the car owner who might actually be an employee of the firm.
In the case of property agent Edwin Kheng, his 1,500cc Honda City carries details like the name of his company (HSR Property Group) and logo, plus his contact number and photo.
The tie-up is also a plus for his career. Said Mr Kheng, 33: 'With car decals, people know I'm the resident property agent in that area and might call me if they ever need help.'
Decals can cost anything from the low tens to thousands of dollars for more fancy designs.
And then there are the drivers who put up their own money for decals, with lofty goals in mind.
Civil servant Terence Soo, 29, has a decal on his Nissan Latio's bumper that displays the website address of Goducate, a non-profit organisation which he volunteers with.
Set up in 2008, it helps improve literacy levels among poverty- stricken children in South-east Asia.
Of the $12 decal, he said: 'It makes sense for individual volunteers to help this way, rather than by donating just a dollar once in a while.'
A spokesman for the Land Transport Authority said it has guidelines on ad placements. The stickers must not be more than 15cm measured from the top edge of the front windscreen, and not more than 10cm measured from the top edge of the rear windscreen and side windows.
The basic colour of the vehicle must also be maintained. This rules out full-body wrapping using vinyl stickers.
The Traffic Police said owners seeking to put advertisements on their vehicles must first get a permit.
Offenders can be fined up to $1,000 or jailed up to three months, or in the case of a second or subsequent offence, a fine of up to $2,000 or jail term of up to six months.
No permit, no display ad
By Melissa Pang

Housing agent Fabien Tan replaced a 4m by 2m banner ad with this smaller one after he was told the huge one was illegal. The BCA rules state that all outdoor ads - regardless of size - must have a licence. -- ST PHOTO: WONG KWAI CHOW
You could not have missed it if you had been walking or driving near the Lorong Chuan area last month.
A huge 4m by 2m banner advertising a home sale was draped over the fence at the back of a semi-detached house in Li Hwan estate.
It read 'For Sale Semi-detached $2.6 million' and gave the telephone number of the housing agent.
But the canvas display has since been taken down - and replaced with a much smaller one - because it broke the rules.
The banner was put up by housing agent Fabien Tan, 28, who felt that traditional publicity methods such as newspaper and online ads and fliers were either too expensive or took too much time to distribute.
So he spent $200 for the giant banner and placed it at the back of the house because it faces a busy traffic junction between Lorong Chuan and Ang Mo Kio Avenue 1.
But about a week after the banner went up, he was told by the Land Transport Authority to take it down as it was illegal and posed a danger to motorists.
He was also told that he would be fined if it was not removed.
Under Building and Construction Authority (BCA) rules, all forms of outdoor advertisements - regardless of size and where they are placed - must have a licence.
Outdoor advertisements are defined as 'outdoor display of any logo, symbol, sign, notice or other visual device, promoting any goods or services, brands of products or events'.
The rule applies even if the sign is placed within one's property.
The reason, said a BCA spokesman, is 'to ensure that such displays are mounted safely and befit the amenities of the place'.
Anyone who flouts the rules can be fined up to $5,000.
The cost of a display advertisement permit depends on its size. It is about $20 for displays not more than 1 sq m, and $140 for those between 5 sq m and 10 sq m.
Still, Mr Tan considers the $200 well-spent even though the banner was up for only about three weeks and the house remains unsold.
'I got more calls than usual from putting up the banner. But there were nuisance calls too,' he said.
BCA said that in the last year alone, it has compounded about 670 offences of unlicensed display of outdoor advertisement signs and signboards. These were put up by owners of properties, advertisers or advertising companies. There were 260 offences in 2008.
To curb the growing problem of unlicensed display advertisements, BCA conducts regular enforcement checks.
It also relies on feedback from the public and other relevant authorities.
Most residents in the Li Hwan estate interviewed said they were surprised when they saw the original banner.
Engineer Esmond Chua, 31, said: 'The first thing I thought was, 'Wow! It's very huge.' I was quite shocked when I saw it and thought it was quite distracting.'
But others did not mind.
Student Dylan Teoh, 18, thinks such banners are acceptable 'as long as it does not encroach on other people's space'.
--------------------------------------------------------------------------------
It pays to drive home a point
By Ng Hui Ying

More people, such as Mr Edwin Kheng from HSR Property Group, are using their cars to carry advertisements for themselves and other companies. The traffic police say those who wish to do so must first apply for a permit. -- ST PHOTO: KEVIN LIM
You must have seen those cars carrying advertisements for property agents or food companies.
But not many know that car owners can actually sell space on their vehicles for such promotional purposes.
Mr Johnson Soh, 42, manager of decal company Soh Guan Chuan Auto Supply, said more than 10 companies have approached him to find willing car owners. The carrot? Some firms foot the road tax for the owner's car - between $1,000 and $1,500 a year for a 1,600cc car - while others hand out petrol vouchers worth $500 to $1,000.
The companies are in fields ranging from liquor to health products and frozen food.
GenConcept, another decal company, said it has seen 50 per cent more enquiries over the past few years concerning advertising on both cars and commercial vehicles.
Renvertising, a company that specialises in advertising on wheels, also helps companies find car owners.
Renvertising's owner, Mr Jeff Peh, 26, said the number of private car owners who have signed on has grown from 220 in 2008 to about 500 now.
One such owner, who wanted to be known only as L. H., said the advertisement his car carries for 3A Car Mats has prompted many of his neighbours to buy the product.
The 33-year-old car dealer, who drives a Proton Wira, is paid $150 a month for his help. That is enough to cover his road tax of $600 and insurance of about $1,000 yearly.
Sometimes, the advertiser works out a win-win deal with the car owner who might actually be an employee of the firm.
In the case of property agent Edwin Kheng, his 1,500cc Honda City carries details like the name of his company (HSR Property Group) and logo, plus his contact number and photo.
The tie-up is also a plus for his career. Said Mr Kheng, 33: 'With car decals, people know I'm the resident property agent in that area and might call me if they ever need help.'
Decals can cost anything from the low tens to thousands of dollars for more fancy designs.
And then there are the drivers who put up their own money for decals, with lofty goals in mind.
Civil servant Terence Soo, 29, has a decal on his Nissan Latio's bumper that displays the website address of Goducate, a non-profit organisation which he volunteers with.
Set up in 2008, it helps improve literacy levels among poverty- stricken children in South-east Asia.
Of the $12 decal, he said: 'It makes sense for individual volunteers to help this way, rather than by donating just a dollar once in a while.'
A spokesman for the Land Transport Authority said it has guidelines on ad placements. The stickers must not be more than 15cm measured from the top edge of the front windscreen, and not more than 10cm measured from the top edge of the rear windscreen and side windows.
The basic colour of the vehicle must also be maintained. This rules out full-body wrapping using vinyl stickers.
The Traffic Police said owners seeking to put advertisements on their vehicles must first get a permit.
Offenders can be fined up to $1,000 or jailed up to three months, or in the case of a second or subsequent offence, a fine of up to $2,000 or jail term of up to six months.
ST : Consider these
May 2, 2010
Consider these
1 Loan tenor
A longer loan repayment period generally means smaller monthly repayments, while a shorter tenor may lead to lower interest paid, although repayments will be higher.
It is worth considering the optimal loan tenor as it affects monthly repayments and interest paid.
Instead of going to either extreme, consider matching the loan tenor to your intended retirement age.
If you are 42, for example, you can take up a 20-year loan that will be paid off by the time you retire at 62.
Financial Alliance associate director Tea Eng Peng says that if you choose a longer loan tenor, you should take up mortgage insurance with a critical illness cover. This will hedge the risk that you are unable to make your monthly repayments due to premature death or disability.
2 Affordability
Before taking the loan, calculate your debt service ratio. It is the percentage of your monthly income needed to service long-term liabilities.
A healthy debt servicing ratio - debt divided by income - should be 35 per cent or less.
'A good rule to follow is to buy what you need and can afford, not what you want and desire and then have to burn the candle at both ends to cough up the monthly mortgage repayment,' said Mr Apelles Poh, a financial planner with Professional Investment Advisory Services.
3 Fixed or variable packages
Fixed packages are suitable for consumers who want to know how much their instalments are for a set period.
With fixed packages, the monthly instalments are not open to fluctuations.
'Fixing the rates for the next few years, the advantage is that you can have peace of mind and you can predict or budget easily,' says Mr Dennis Ng, spokesman for www.HousingLoanSG.com - a mortgage consultancy portal.
'The disadvantage is that banks typically charge higher interest rates for fixed-rate packages, and you might end up paying higher interest if interest rates remain stable or low.'
Mr Ng says variable packages typically come with shorter lock-in periods.
For variable packages, the loan is usually linked to one of two major benchmark rates: Singapore Interbank Offered Rate (Sibor) or the Swap Offer Rate (SOR).
Experts say that as soon as the United States starts to raise interest rates, which could be as early as the end of this year, local interest rates will follow suit.
4 Early payment options
Not all loans allow customers to settle early,
so check the fine print before signing up. An early settlement fee is usually imposed if a loan is paid off early.
'A cancellation of the loan with the lock-in period often entails a penalty of, say 1 per cent of outstanding loan, and a claw-back of legal subsidy, valuation fees and fire insurance premiums,' Mr Poh says.
Consider these
1 Loan tenor
A longer loan repayment period generally means smaller monthly repayments, while a shorter tenor may lead to lower interest paid, although repayments will be higher.
It is worth considering the optimal loan tenor as it affects monthly repayments and interest paid.
Instead of going to either extreme, consider matching the loan tenor to your intended retirement age.
If you are 42, for example, you can take up a 20-year loan that will be paid off by the time you retire at 62.
Financial Alliance associate director Tea Eng Peng says that if you choose a longer loan tenor, you should take up mortgage insurance with a critical illness cover. This will hedge the risk that you are unable to make your monthly repayments due to premature death or disability.
2 Affordability
Before taking the loan, calculate your debt service ratio. It is the percentage of your monthly income needed to service long-term liabilities.
A healthy debt servicing ratio - debt divided by income - should be 35 per cent or less.
'A good rule to follow is to buy what you need and can afford, not what you want and desire and then have to burn the candle at both ends to cough up the monthly mortgage repayment,' said Mr Apelles Poh, a financial planner with Professional Investment Advisory Services.
3 Fixed or variable packages
Fixed packages are suitable for consumers who want to know how much their instalments are for a set period.
With fixed packages, the monthly instalments are not open to fluctuations.
'Fixing the rates for the next few years, the advantage is that you can have peace of mind and you can predict or budget easily,' says Mr Dennis Ng, spokesman for www.HousingLoanSG.com - a mortgage consultancy portal.
'The disadvantage is that banks typically charge higher interest rates for fixed-rate packages, and you might end up paying higher interest if interest rates remain stable or low.'
Mr Ng says variable packages typically come with shorter lock-in periods.
For variable packages, the loan is usually linked to one of two major benchmark rates: Singapore Interbank Offered Rate (Sibor) or the Swap Offer Rate (SOR).
Experts say that as soon as the United States starts to raise interest rates, which could be as early as the end of this year, local interest rates will follow suit.
4 Early payment options
Not all loans allow customers to settle early,
so check the fine print before signing up. An early settlement fee is usually imposed if a loan is paid off early.
'A cancellation of the loan with the lock-in period often entails a penalty of, say 1 per cent of outstanding loan, and a claw-back of legal subsidy, valuation fees and fire insurance premiums,' Mr Poh says.
ST : Dream Home Loans
May 2, 2010
Dream Home Loans
The Sunday Times checks out the best offerings from some banks
By Gabriel Chen , Harsha Jethnani
If you thought low mortgage rates would stay unchanged this year, think again.
Over the last month or so, some banks have upped the spreads they charge above Sibor - the rate at which banks lend to one another - making Sibor-pegged home loans more expensive.
The three-month Singapore Interbank Offered Rate, or Sibor, was at 0.54 per cent last week, below the previous all-time low of 0.56 per cent in June 2003.
At DBS Bank, a home-buyer taking a loan of 80 per cent of his property's value around March would have paid a rate of Sibor plus 0.5 percentage point for the first year and Sibor plus 0.75 percentage point for the second.
A buyer opting for this Sibor- linked DBS package now will have to pay Sibor plus 1 percentage point for the first two years.
Some fixed-rate packages have also shot up recently.
Standard Chartered Bank's one-year fixed package stood at 1.25 per cent in March, but has risen to 1.95 per cent.
Sibor, which is already low as it tracks prevailing United States rates which are at rock bottom, fell further following gains in the Singapore dollar last month.
In line with the improving global economic outlook, interest rates in some countries have moved higher - with more rate hikes expected globally in the second half of the year.
Some experts tip Sibor to rise later this year and to go even higher from next year.
Standard Chartered economist Alvin Liew predicts the three-month Sibor rate will likely rise to 3 per cent in 2012.
'Mortgage rates are hitting one of the lowest levels in recent years,' says Providend's head of financial planning, Mr Eddy Cheong. 'I think, going forward, there is a high chance that rates will move up if the economy continues to improve.'
When interest rates rise, monthly instalments on home loans that are not fixed will be driven up.
This could have severe implications for buyers who have over- extended themselves with big mortgages, believing interest rates will always stay low.
'Do your numbers properly. Buying a home should be a blessing, not burden,' says Mr Apelles Poh, a financial planner with Professional Investment Advisory Services.
While some home loan rates are now higher, there are still bargains and benefits out there for the cost-conscious home-buyer.
The Sunday Times shopped around to find out what some banks have to offer:
Fixed-rate loans
If you want loans with fixed rates locked in for a term of three or five years, try DBS Bank.
Last week, the bank introduced its five-year fixed package, an unusual tenor in the market.
· Rates: Three-year package: The bank's current promotion requires a customer to also sign up for its mortgage insurance plan. Rates are fixed at 1.99 per cent for three years, and Sibor plus 1.25 per cent thereafter.
Standard rates are otherwise 2.2 per cent for three years, and Sibor plus 1.5 per cent thereafter.
Five-year package: For those taking up mortgage protection as well, rates are 2.25 per cent for five years and then Sibor plus 1.25 per cent.
Standard rates are 2.5 per cent for five years, and Sibor plus 1.5 per cent thereafter.
The managing director and head of DBS' consumer banking group, Mr Jeremy Soo, says: 'Our three-year fixed rate remains highly popular with home owners desiring more certainty in their repayment, especially with our three- and five- year fixed rates at a historical low'.
He says the current promotion includes mortgage protection, which is a 'key consideration for many home owners since mortgage is a long-term and significant commitment'.
Sibor-linked loans
If you are exploring Sibor-linked loans, HSBC will be the bank of choice. Its 'no lock-in' Sibor-pegged loyalty home loan is the only package that offers decreasing spreads over the tenor.
· Rates: You pay the three-month Sibor plus an additional 0.9 per cent for the first year, three-month Sibor plus 0.8 per cent for the second year and then the three-month Sibor plus 0.7 per cent thereafter.
'The interest spread reduction feature serves to benefit customers regardless of how Sibor rates move,' says Mr Sebastian Arcuri, head of personal financial services at HSBC Singapore.
This bucks the conventional home loan package, which typically sees interest rate spreads rise over the loan tenor, he adds.
Sibor-linked loans with flexibility
Citibank provides the best solutions if you are looking for flexibility through the widest variety of Sibor- linked loans.
Unlike other banks, Citi offers loans pegged to the one-month Sibor. Other loans are pegged to the three-, six- and 12-month Sibor. Lock-in period varies from zero to two years, and spreads are determined based on the size of the loan and customer relationship.
Citi offers the lowest rate on one-year fixed packages at 1.5 per cent. For its two-year fixed package, it charges 1.88 per cent for the first two years.
· Rates: For the first year, rates are Sibor plus 0.7 per cent to 1 per cent. For year two, rates are Sibor plus 0.9 per cent to 1 per cent, and thereafter Sibor plus 1 per cent to 1.25 per cent.
'Customers have the flexibility to switch from one tenor to another upon tenor maturity date,' says the business director for secured finance at Citibank Singapore, Ms Vibha Coburn.
As an example, clients can make use of the low one-month Sibor and subsequently, when the month is over, perhaps pick a 12-month Sibor if they feel that interest rates are likely to rise.
SOR-linked loans
For loans tied to the Swap Offer Rate, or SOR, OCBC and United Overseas Bank (UOB) are good picks.
UOB offers a package tied to the one-month SOR, now at 0.35 per cent, that allows customers to pay a fixed monthly instalment for a one-year period.
· Rates: For the first three years, rates are one-month SOR plus 1.25 per cent, and thereafter the one- month SOR plus 1.5 per cent.
In the first year, if interest rates increase, 'customers can be assured that their monthly cash flow will not be disrupted. Conversely, if the rates decline, customers can pay off more of the principal amount', says a UOB spokesman.
The one-year constant monthly instalment feature can be re-continued for subsequent years as the fixed monthly instalments will be re-computed based on the remaining tenor and interest.
SOR-linked with lowest rates
OCBC offers the lowest rates on loans pegged to the three-month SOR, which is hovering at around 0.39 per cent, with a two-year lock-in.
· Rates: SOR plus 0.75 per cent for the first year, SOR plus 1 per cent for the second year, SOR plus 1.25 per cent for the third year and SOR plus 1.5 per cent thereafter.
Ms Phang Lah Hwa, OCBC's head of consumer secured lending, advises buyers to guard against being swayed by just their sentiments.
Properly assessing your financial ability before making a commitment is important, she says.
'Consider longer-term issues, like affordability in the event that interest rates rise or instalment amounts increase,' adds Ms Phang.
Loans with variable rates
As for loans with variable rates, Maybank emerges the top of the lot, with the most affordable rates, with a two-year lock-in.
· Rates: The loans are tied to the bank's board rate, currently at 3.75 per cent.
Rates on the loans are discounted from this 3.75 per cent, starting at 1.18 per cent for the first year. Customers will pay 1.68 per cent in the second year, and then 2.28 per cent in the third year, and 3.25 per cent thereafter.
To mark its 50th anniversary, Maybank is offering a cash gift of $5,000 to customers who pick up the variable-rate loan, says consumer banking head Helen Neo.
Rates for loans inclusive of the gift are slightly different, at 1.68 per cent for the first year, 1.88 per cent for the second year, 2.38 per cent for the third, and 3.25 per cent thereafter.
The two packages offer 'customers discounts off the bank's board rate throughout the period of their loan tenor', Ms Neo adds.
gabrielc@sph.com.sg
harshamj@sph.com.sg
Dream Home Loans
The Sunday Times checks out the best offerings from some banks
By Gabriel Chen , Harsha Jethnani
If you thought low mortgage rates would stay unchanged this year, think again.
Over the last month or so, some banks have upped the spreads they charge above Sibor - the rate at which banks lend to one another - making Sibor-pegged home loans more expensive.
The three-month Singapore Interbank Offered Rate, or Sibor, was at 0.54 per cent last week, below the previous all-time low of 0.56 per cent in June 2003.
At DBS Bank, a home-buyer taking a loan of 80 per cent of his property's value around March would have paid a rate of Sibor plus 0.5 percentage point for the first year and Sibor plus 0.75 percentage point for the second.
A buyer opting for this Sibor- linked DBS package now will have to pay Sibor plus 1 percentage point for the first two years.
Some fixed-rate packages have also shot up recently.
Standard Chartered Bank's one-year fixed package stood at 1.25 per cent in March, but has risen to 1.95 per cent.
Sibor, which is already low as it tracks prevailing United States rates which are at rock bottom, fell further following gains in the Singapore dollar last month.
In line with the improving global economic outlook, interest rates in some countries have moved higher - with more rate hikes expected globally in the second half of the year.
Some experts tip Sibor to rise later this year and to go even higher from next year.
Standard Chartered economist Alvin Liew predicts the three-month Sibor rate will likely rise to 3 per cent in 2012.
'Mortgage rates are hitting one of the lowest levels in recent years,' says Providend's head of financial planning, Mr Eddy Cheong. 'I think, going forward, there is a high chance that rates will move up if the economy continues to improve.'
When interest rates rise, monthly instalments on home loans that are not fixed will be driven up.
This could have severe implications for buyers who have over- extended themselves with big mortgages, believing interest rates will always stay low.
'Do your numbers properly. Buying a home should be a blessing, not burden,' says Mr Apelles Poh, a financial planner with Professional Investment Advisory Services.
While some home loan rates are now higher, there are still bargains and benefits out there for the cost-conscious home-buyer.
The Sunday Times shopped around to find out what some banks have to offer:
Fixed-rate loans
If you want loans with fixed rates locked in for a term of three or five years, try DBS Bank.
Last week, the bank introduced its five-year fixed package, an unusual tenor in the market.
· Rates: Three-year package: The bank's current promotion requires a customer to also sign up for its mortgage insurance plan. Rates are fixed at 1.99 per cent for three years, and Sibor plus 1.25 per cent thereafter.
Standard rates are otherwise 2.2 per cent for three years, and Sibor plus 1.5 per cent thereafter.
Five-year package: For those taking up mortgage protection as well, rates are 2.25 per cent for five years and then Sibor plus 1.25 per cent.
Standard rates are 2.5 per cent for five years, and Sibor plus 1.5 per cent thereafter.
The managing director and head of DBS' consumer banking group, Mr Jeremy Soo, says: 'Our three-year fixed rate remains highly popular with home owners desiring more certainty in their repayment, especially with our three- and five- year fixed rates at a historical low'.
He says the current promotion includes mortgage protection, which is a 'key consideration for many home owners since mortgage is a long-term and significant commitment'.
Sibor-linked loans
If you are exploring Sibor-linked loans, HSBC will be the bank of choice. Its 'no lock-in' Sibor-pegged loyalty home loan is the only package that offers decreasing spreads over the tenor.
· Rates: You pay the three-month Sibor plus an additional 0.9 per cent for the first year, three-month Sibor plus 0.8 per cent for the second year and then the three-month Sibor plus 0.7 per cent thereafter.
'The interest spread reduction feature serves to benefit customers regardless of how Sibor rates move,' says Mr Sebastian Arcuri, head of personal financial services at HSBC Singapore.
This bucks the conventional home loan package, which typically sees interest rate spreads rise over the loan tenor, he adds.
Sibor-linked loans with flexibility
Citibank provides the best solutions if you are looking for flexibility through the widest variety of Sibor- linked loans.
Unlike other banks, Citi offers loans pegged to the one-month Sibor. Other loans are pegged to the three-, six- and 12-month Sibor. Lock-in period varies from zero to two years, and spreads are determined based on the size of the loan and customer relationship.
Citi offers the lowest rate on one-year fixed packages at 1.5 per cent. For its two-year fixed package, it charges 1.88 per cent for the first two years.
· Rates: For the first year, rates are Sibor plus 0.7 per cent to 1 per cent. For year two, rates are Sibor plus 0.9 per cent to 1 per cent, and thereafter Sibor plus 1 per cent to 1.25 per cent.
'Customers have the flexibility to switch from one tenor to another upon tenor maturity date,' says the business director for secured finance at Citibank Singapore, Ms Vibha Coburn.
As an example, clients can make use of the low one-month Sibor and subsequently, when the month is over, perhaps pick a 12-month Sibor if they feel that interest rates are likely to rise.
SOR-linked loans
For loans tied to the Swap Offer Rate, or SOR, OCBC and United Overseas Bank (UOB) are good picks.
UOB offers a package tied to the one-month SOR, now at 0.35 per cent, that allows customers to pay a fixed monthly instalment for a one-year period.
· Rates: For the first three years, rates are one-month SOR plus 1.25 per cent, and thereafter the one- month SOR plus 1.5 per cent.
In the first year, if interest rates increase, 'customers can be assured that their monthly cash flow will not be disrupted. Conversely, if the rates decline, customers can pay off more of the principal amount', says a UOB spokesman.
The one-year constant monthly instalment feature can be re-continued for subsequent years as the fixed monthly instalments will be re-computed based on the remaining tenor and interest.
SOR-linked with lowest rates
OCBC offers the lowest rates on loans pegged to the three-month SOR, which is hovering at around 0.39 per cent, with a two-year lock-in.
· Rates: SOR plus 0.75 per cent for the first year, SOR plus 1 per cent for the second year, SOR plus 1.25 per cent for the third year and SOR plus 1.5 per cent thereafter.
Ms Phang Lah Hwa, OCBC's head of consumer secured lending, advises buyers to guard against being swayed by just their sentiments.
Properly assessing your financial ability before making a commitment is important, she says.
'Consider longer-term issues, like affordability in the event that interest rates rise or instalment amounts increase,' adds Ms Phang.
Loans with variable rates
As for loans with variable rates, Maybank emerges the top of the lot, with the most affordable rates, with a two-year lock-in.
· Rates: The loans are tied to the bank's board rate, currently at 3.75 per cent.
Rates on the loans are discounted from this 3.75 per cent, starting at 1.18 per cent for the first year. Customers will pay 1.68 per cent in the second year, and then 2.28 per cent in the third year, and 3.25 per cent thereafter.
To mark its 50th anniversary, Maybank is offering a cash gift of $5,000 to customers who pick up the variable-rate loan, says consumer banking head Helen Neo.
Rates for loans inclusive of the gift are slightly different, at 1.68 per cent for the first year, 1.88 per cent for the second year, 2.38 per cent for the third, and 3.25 per cent thereafter.
The two packages offer 'customers discounts off the bank's board rate throughout the period of their loan tenor', Ms Neo adds.
gabrielc@sph.com.sg
harshamj@sph.com.sg
ST : Big tenants moving from Raffles Place
May 1, 2010
Big tenants moving from Raffles Place
But some experts are upbeat vacant space will be absorbed
By Esther Teo
AS LARGE tenants prepare to move into gleaming new offices, including the much-anticipated Marina Bay Financial Centre (MBFC), landlords at older office blocks are searching for replacements.
'Raffles Place will be particularly hard hit, with five to six buildings seeing major tenants relocate to either MBFC or new schemes in Tanjong Pagar,' said office leasing agent Corporate Locations director Edmund Goh.
The mini exodus includes companies such as Barclays Capital, Normura, Macquarie and Standard Chartered, which have announced their impending moves to newly minted space such as MBFC.
CB Richard Ellis estimates a vast 4.1million sq ft of Grade A office space will be ready this year and next, including MBFC and Ocean Financial Centre.
Broadly speaking, rents at these new office buildings tend to be somewhat higher than the likes of Raffles Place.
The take-up of this spanking new space means a large pool of office space could be left vacant in coming months.
The MBFC's first phase - commercial towers one and two, boasting about 1.6million sq ft - will be ready in the third quarter and is almost fully leased apart from a small percentage reserved for existing tenants' expansion.
However, experts say that its full impact on rents will not be felt till the last quarter of this year, when the actual relocation begins and asset managers have a clearer picture of occupancy rates.
Ms June Chua, director of commercial leasing at Savills Singapore, said she is 'cautiously optimistic' vacant space will be absorbed. 'Vacancy levels at some of the older buildings will definitely increase and we might start seeing rental corrections early next year... But there is no firm general trend as rentals are building-specific depending on occupancy rates, which have not yet been finalised.'
Other experts, however, are more optimistic. They say older buildings are unlikely to see a hollowing out as leasing activity has been picking up in tandem with the robust economic recovery.
Firms that held off expansion amid the recession are gearing up to take advantage of competitive rents, they say. Smaller firms might also see this as a chance to get a foothold in prime areas.
Citi Private Bank co-head of global real estate Quek Kwang-Meng said that while larger tenants have flocked to newer projects, older and less pricey Grade A office space will still be in demand as this caters to smaller tenants such as law firms.
Knight Frank group managing director Danny Yeo said that with an influx of new foreign firms, he does not expect older Grade A offices to remain vacant for long. He expects rents to stabilise this year and possibly rise next year if the recovery is sustained.
'Large financial services might require large spaces at MBFC but there are smaller funds or companies which are not suited for that location... Raffles Place is not a concern, I might be more worried about Robinson Road instead, although it is still too early to tell.'
Some real estate investment trusts said that despite losing tenants, the high pre-commitment levels in new developments reflected healthy market demand.
Mr Andy Tan, senior vice-president of MEAG Pacific Star Asset Management - the manager of Capital Square, which houses units of Barclays and Macquarie - said net absorption of office space has stayed positive for the last three quarters.
'This is a sign of improving conditions and with the economy on the growth track and employment expected to continue on the uptrend, the demand and growth of the office market is still sustainable. We remain confident of Capital Square's potential and are... in the process of securing new tenants,' he said.
CapitaCommercial Trust Management chief executive Lynette Leong said there are clear signs that office demand has recovered and that office market rentals may have reached a trough.
'We do not think there will be a significant hollowing out of office space from Raffles Place.' Given the rebound in demand, vacated space could easily be filled by tenants who need to expand or new tenants attracted to the area, she said.
However, the largely uncommitted new office supply of 4.5 million sq ft projected for next year and 2012 still leaves a question as to when office market rentals will recover and to what degree, she said.
esthert@sph.com.sg
--------------------------------------------------------------------------------
TWO SCENARIOS
· Departure of major players from Raffles Place causes rents in area to fall
· Smaller firms grab chance to move into prime office space, so hollowing out effect is temporary

Experts do not expect a hollowing out of office space from Raffles Place (above) although some of its major tenants are relocating to newly minted space elsewhere, as they say leasing activity has been picking up in tandem with the robust economic recovery. -- ST PHOTO: ALPHONSUS CHERN
Big tenants moving from Raffles Place
But some experts are upbeat vacant space will be absorbed
By Esther Teo
AS LARGE tenants prepare to move into gleaming new offices, including the much-anticipated Marina Bay Financial Centre (MBFC), landlords at older office blocks are searching for replacements.
'Raffles Place will be particularly hard hit, with five to six buildings seeing major tenants relocate to either MBFC or new schemes in Tanjong Pagar,' said office leasing agent Corporate Locations director Edmund Goh.
The mini exodus includes companies such as Barclays Capital, Normura, Macquarie and Standard Chartered, which have announced their impending moves to newly minted space such as MBFC.
CB Richard Ellis estimates a vast 4.1million sq ft of Grade A office space will be ready this year and next, including MBFC and Ocean Financial Centre.
Broadly speaking, rents at these new office buildings tend to be somewhat higher than the likes of Raffles Place.
The take-up of this spanking new space means a large pool of office space could be left vacant in coming months.
The MBFC's first phase - commercial towers one and two, boasting about 1.6million sq ft - will be ready in the third quarter and is almost fully leased apart from a small percentage reserved for existing tenants' expansion.
However, experts say that its full impact on rents will not be felt till the last quarter of this year, when the actual relocation begins and asset managers have a clearer picture of occupancy rates.
Ms June Chua, director of commercial leasing at Savills Singapore, said she is 'cautiously optimistic' vacant space will be absorbed. 'Vacancy levels at some of the older buildings will definitely increase and we might start seeing rental corrections early next year... But there is no firm general trend as rentals are building-specific depending on occupancy rates, which have not yet been finalised.'
Other experts, however, are more optimistic. They say older buildings are unlikely to see a hollowing out as leasing activity has been picking up in tandem with the robust economic recovery.
Firms that held off expansion amid the recession are gearing up to take advantage of competitive rents, they say. Smaller firms might also see this as a chance to get a foothold in prime areas.
Citi Private Bank co-head of global real estate Quek Kwang-Meng said that while larger tenants have flocked to newer projects, older and less pricey Grade A office space will still be in demand as this caters to smaller tenants such as law firms.
Knight Frank group managing director Danny Yeo said that with an influx of new foreign firms, he does not expect older Grade A offices to remain vacant for long. He expects rents to stabilise this year and possibly rise next year if the recovery is sustained.
'Large financial services might require large spaces at MBFC but there are smaller funds or companies which are not suited for that location... Raffles Place is not a concern, I might be more worried about Robinson Road instead, although it is still too early to tell.'
Some real estate investment trusts said that despite losing tenants, the high pre-commitment levels in new developments reflected healthy market demand.
Mr Andy Tan, senior vice-president of MEAG Pacific Star Asset Management - the manager of Capital Square, which houses units of Barclays and Macquarie - said net absorption of office space has stayed positive for the last three quarters.
'This is a sign of improving conditions and with the economy on the growth track and employment expected to continue on the uptrend, the demand and growth of the office market is still sustainable. We remain confident of Capital Square's potential and are... in the process of securing new tenants,' he said.
CapitaCommercial Trust Management chief executive Lynette Leong said there are clear signs that office demand has recovered and that office market rentals may have reached a trough.
'We do not think there will be a significant hollowing out of office space from Raffles Place.' Given the rebound in demand, vacated space could easily be filled by tenants who need to expand or new tenants attracted to the area, she said.
However, the largely uncommitted new office supply of 4.5 million sq ft projected for next year and 2012 still leaves a question as to when office market rentals will recover and to what degree, she said.
esthert@sph.com.sg
--------------------------------------------------------------------------------
TWO SCENARIOS
· Departure of major players from Raffles Place causes rents in area to fall
· Smaller firms grab chance to move into prime office space, so hollowing out effect is temporary

Experts do not expect a hollowing out of office space from Raffles Place (above) although some of its major tenants are relocating to newly minted space elsewhere, as they say leasing activity has been picking up in tandem with the robust economic recovery. -- ST PHOTO: ALPHONSUS CHERN
ST : Designed to wow
May 1, 2010
Designed to wow
Move over sky gardens and glass gyms, new condos boast outdoor jacuzzis and treehouses
By tay suan chiang
With new condominium launches popping up so frequently, developers are going all out to woo buyers with apartments that come with unique features.
So forget sky gardens, all-glass gyms overlooking the swimming pool and communal lap pools. Once to-die-for, such facilities are becoming a dime a dozen.
Instead, drool over personal pools, en- suite 'sky garages' for high-rise apartments, penthouses with private spa tubs and outdoor showers and baths.
However, these wow factors come at a price - apartments with such features usually fall in the $2 million-plus range.
One of the newest residential projects to offer a different way of condo living is UOL Group's Waterbank at Dakota. Apart from the usual studio, two-, three- and four-bedroom units, there is a row of 11 'cabana' units that cost about $1.3 million each.
Cabanas, Spanish for cabins, are usually shelters on a beach or by a swimming pool. But at the Waterbank, think resort- style residential units with all the comforts of an apartment.
The two-bedroom cabana homes, which are built on top of the multi-storey carpark, have outdoor showers and a common 50m lap pool at the doorstep.
The idea of strolling out to a pool at your front door as if you were on a holiday getaway sure is appealing. Nine of the cabanas have been sold since their launch two weeks ago. They are expected to be ready by 2014.
Engineer Nigel Chu, who is in his 30s, is one of the buyers. The avid swimmer, who paid $1.32 million for his 1,421 sq ft unit, was looking for an apartment that had direct access to the pool.
'Buying a ground floor unit means having other units above me, which I didn't like,' he says. The cabana unit suits him better and 'I also like that it has a large patio', he adds.
Apart from cabana units, UOL has also introduced various 'wow' features in its other developments, such as 'treehouse' units at Meadows @ Peirce and private pools at Nassim Park Residences.
UOL chief operating officer Liam Wee Sin says: 'We constantly create new and interesting prototypes in each of our projects to introduce variety to Singapore's housing market. With the homebuyers in mind, we come up with unique prototypes with a strong focus on design and lifestyle.' A registered architect, he came up with the idea of the cabana units.
In 2008, developer Hayden Properties made headlines with the launch of its high-end luxury condo Hamilton Scotts.
Units in this development come with en-suite sky garages, allowing residents to park their cars right in their homes. The apartments are priced from $2,700 per sq ft and there are 'some units' left, according to a Hayden sales consultant.
The project, which is due for completion next year, is the first in Asia to feature sky garages. Hayden's founder, Ms Ong Chih Ching, said in an earlier report that 'we wanted something flamboyant and high-end... new and creative'.
The Marq On Paterson Hill, which was launched by upmarket developer SC Global in 2007, boasts another first in Singapore. Every apartment in one of its towers will have a cantilevered 15m lap pool. Swimmers can enjoy views of Orchard Road while doing laps.
According to SC Global, 'buyers who seek the benefits of a good-class bungalow - the luxury of space, airiness, an outdoor pool - will find it in The Marq'.
In 2007, one of these units sold for $31 million.
While The Marq stands out literally, several developers are offering the luxury of private jet pools and outdoor baths.
Among them is City Developments (CDL), which in 2006 introduced private jacuzzis and pools on the roof terrace of penthouses at The Oceanfront @ Sentosa Cove.
A CDL spokesman says that 'because of the development's unique location at the edge of the waterfront, residents living in these apartments can enjoy magnificent ocean views while relaxing in their private pool and jacuzzi'.
He adds that 'with positive feedback from homebuyers, we have gone on to include similar features selectively in our more recent developments'.
Luxury features drive up costs
For example, at the developer's Volari at Balmoral, all the four-bedroom units have private jet pools in the balconies, while the penthouses have pools on the roof terraces.
'These exclusive features resonate well with consumers looking for a luxurious, indulgent and unique lifestyle experience,' says CDL.
Private outdoor baths can be found in Wing Tai Group's L'Viv at Newton. They are in its 72 two-bedroom-plus-study units, which cost from $2 million each. More than 85 per cent of the units that were launched last month have been sold, says a Wing Tai spokesman.
He adds: 'We see a growing trend where buyers are placing more importance on their 'bath' experience, possibly from their enjoyment of top-end resort villas in Bali and the Maldives. We are excited to bring to this development a 'getaway retreat'.'
Property expert Chris Koh, who is a director at Dennis Wee Group, says developers introduce exclusive features 'to make their developments stand out from the rest and to offer residents a lifestyle that is different from that of typical condos'.
He adds that because such features tend to drive up construction costs, they are likely to be offered only in luxury developments.
He does not think the trend will catch on in suburban developments as the prices will be out of reach for buyers in that segment.
Still, not everyone is wowed by the features that developers are throwing in.
'Ultimately, a home that is spacious and conveniently located is what matters to me,' says financial consultant Bernard Lee, 50. 'These features are a luxury but they are just costly extras that will lose their novelty eventually.'
taysc@sph.com.sg
--------------------------------------------------------------------------------

Wow factor: Private jet pools and steam spa rooms
Where: Hilltops by SC Global; The Oceanfront @ Sentosa Cove and Volari by City Developments; and L'Viv by Wing Tai Group
What: It is no longer enough for condos to offer communal hot tubs and steam rooms. Hilltops in Cairnhill Road offers resort-style steam spa rooms in all apartments. In 2006, CDL introduced private jacuzzis and pools on the roof terrace of the penthouses at The Oceanfront @ Sentosa Cove.
At Volari in Balmoral Road, its four- bedroom units each comes with a jet pool in the balcony. Jet pools are also available in its penthouses, which also have sky pools in the terraces.

At L'Viv in Newton Road, its two- bedroom-plus-study units come with a private outdoor jacuzzi in the master bathroom.

Wow factor: Cabana apartments
Where: Waterbank at Dakota by UOL Group
What: At this newly launched project, the cabana units, the first of their kind in Singapore, are a row of 11 two-bedroom units built on top of the multi-storey carpark. The units come with an outdoor shower, face a 50m lap pool and have direct access to hot tubs and rain showers on the same deck.

Wow factor: Treehouse apartments
Where: Meadows @ Peirce by UOL
What: Three four-bedroom units on the second floor each comes with an outdoor terrace and a 'treehouse' that is about the size of a bedroom. The spot is great for barbecues and for children to do some camping without having to leave home. All three units have been sold.

Wow factor: En-suite sky garages
Where: Hamilton Scotts by Hayden Properties
What: Home owners who are so attached to their cars that they cannot bear to leave them in a carpark can now park them next to their living rooms - in their high-rise apartments. The high-end condo in Scotts Road is the first in Asia to have en-suite 'sky garages'.
The parking space, which can fit two cars, is separated from the living area by double-glazed glass. Drivers stop their vehicles at a designated point in the basement, exit and undergo a biometric scan, whereupon a lift transports the car to the correct unit in an automated, driverless process. No need to worry about reversing out the window.
Wow factor: Private lap pools
Where: The Marq On Paterson Hill by SC Global; Nassim Park Residences by UOL; and The Stellar, Elliot at the East Coast and Goodwood Residence by Guocoland

What: Yet another first in Singapore - in this case, every apartment in one tower of The Marq, which was launched in 2007, will have a 15m private lap pool that is cantilevered, giving residents water views coupled with the Orchard Road skyline in the background.
Over at UOL's Nassim Park Residences, which was launched in 2008, the ground-floor units and penthouses come with their own swimming pools. They have all been sold.
Guocoland says its developments' special ground-floor units, which come with private pools, were snapped up quickly.
Wow factor: Dual-key apartments
Where: Caspian at Lakeside, 8@Woodleigh and Flamingo Valley at Siglap, all by Frasers Centrepoint; and Waterbank at Dakota by UOL
What: A smaller unit that is attached to a bigger unit. Each unit comes fully equipped with its own kitchen, bathroom and dining and living areas. They each have their own entrance which opens up to a shared foyer.
With these features, the apartments are great for multi-generational living and for renting.
Designed to wow
Move over sky gardens and glass gyms, new condos boast outdoor jacuzzis and treehouses
By tay suan chiang
With new condominium launches popping up so frequently, developers are going all out to woo buyers with apartments that come with unique features.
So forget sky gardens, all-glass gyms overlooking the swimming pool and communal lap pools. Once to-die-for, such facilities are becoming a dime a dozen.
Instead, drool over personal pools, en- suite 'sky garages' for high-rise apartments, penthouses with private spa tubs and outdoor showers and baths.
However, these wow factors come at a price - apartments with such features usually fall in the $2 million-plus range.
One of the newest residential projects to offer a different way of condo living is UOL Group's Waterbank at Dakota. Apart from the usual studio, two-, three- and four-bedroom units, there is a row of 11 'cabana' units that cost about $1.3 million each.
Cabanas, Spanish for cabins, are usually shelters on a beach or by a swimming pool. But at the Waterbank, think resort- style residential units with all the comforts of an apartment.
The two-bedroom cabana homes, which are built on top of the multi-storey carpark, have outdoor showers and a common 50m lap pool at the doorstep.
The idea of strolling out to a pool at your front door as if you were on a holiday getaway sure is appealing. Nine of the cabanas have been sold since their launch two weeks ago. They are expected to be ready by 2014.
Engineer Nigel Chu, who is in his 30s, is one of the buyers. The avid swimmer, who paid $1.32 million for his 1,421 sq ft unit, was looking for an apartment that had direct access to the pool.
'Buying a ground floor unit means having other units above me, which I didn't like,' he says. The cabana unit suits him better and 'I also like that it has a large patio', he adds.
Apart from cabana units, UOL has also introduced various 'wow' features in its other developments, such as 'treehouse' units at Meadows @ Peirce and private pools at Nassim Park Residences.
UOL chief operating officer Liam Wee Sin says: 'We constantly create new and interesting prototypes in each of our projects to introduce variety to Singapore's housing market. With the homebuyers in mind, we come up with unique prototypes with a strong focus on design and lifestyle.' A registered architect, he came up with the idea of the cabana units.
In 2008, developer Hayden Properties made headlines with the launch of its high-end luxury condo Hamilton Scotts.
Units in this development come with en-suite sky garages, allowing residents to park their cars right in their homes. The apartments are priced from $2,700 per sq ft and there are 'some units' left, according to a Hayden sales consultant.
The project, which is due for completion next year, is the first in Asia to feature sky garages. Hayden's founder, Ms Ong Chih Ching, said in an earlier report that 'we wanted something flamboyant and high-end... new and creative'.
The Marq On Paterson Hill, which was launched by upmarket developer SC Global in 2007, boasts another first in Singapore. Every apartment in one of its towers will have a cantilevered 15m lap pool. Swimmers can enjoy views of Orchard Road while doing laps.
According to SC Global, 'buyers who seek the benefits of a good-class bungalow - the luxury of space, airiness, an outdoor pool - will find it in The Marq'.
In 2007, one of these units sold for $31 million.
While The Marq stands out literally, several developers are offering the luxury of private jet pools and outdoor baths.
Among them is City Developments (CDL), which in 2006 introduced private jacuzzis and pools on the roof terrace of penthouses at The Oceanfront @ Sentosa Cove.
A CDL spokesman says that 'because of the development's unique location at the edge of the waterfront, residents living in these apartments can enjoy magnificent ocean views while relaxing in their private pool and jacuzzi'.
He adds that 'with positive feedback from homebuyers, we have gone on to include similar features selectively in our more recent developments'.
Luxury features drive up costs
For example, at the developer's Volari at Balmoral, all the four-bedroom units have private jet pools in the balconies, while the penthouses have pools on the roof terraces.
'These exclusive features resonate well with consumers looking for a luxurious, indulgent and unique lifestyle experience,' says CDL.
Private outdoor baths can be found in Wing Tai Group's L'Viv at Newton. They are in its 72 two-bedroom-plus-study units, which cost from $2 million each. More than 85 per cent of the units that were launched last month have been sold, says a Wing Tai spokesman.
He adds: 'We see a growing trend where buyers are placing more importance on their 'bath' experience, possibly from their enjoyment of top-end resort villas in Bali and the Maldives. We are excited to bring to this development a 'getaway retreat'.'
Property expert Chris Koh, who is a director at Dennis Wee Group, says developers introduce exclusive features 'to make their developments stand out from the rest and to offer residents a lifestyle that is different from that of typical condos'.
He adds that because such features tend to drive up construction costs, they are likely to be offered only in luxury developments.
He does not think the trend will catch on in suburban developments as the prices will be out of reach for buyers in that segment.
Still, not everyone is wowed by the features that developers are throwing in.
'Ultimately, a home that is spacious and conveniently located is what matters to me,' says financial consultant Bernard Lee, 50. 'These features are a luxury but they are just costly extras that will lose their novelty eventually.'
taysc@sph.com.sg
--------------------------------------------------------------------------------

Wow factor: Private jet pools and steam spa rooms
Where: Hilltops by SC Global; The Oceanfront @ Sentosa Cove and Volari by City Developments; and L'Viv by Wing Tai Group
What: It is no longer enough for condos to offer communal hot tubs and steam rooms. Hilltops in Cairnhill Road offers resort-style steam spa rooms in all apartments. In 2006, CDL introduced private jacuzzis and pools on the roof terrace of the penthouses at The Oceanfront @ Sentosa Cove.
At Volari in Balmoral Road, its four- bedroom units each comes with a jet pool in the balcony. Jet pools are also available in its penthouses, which also have sky pools in the terraces.

At L'Viv in Newton Road, its two- bedroom-plus-study units come with a private outdoor jacuzzi in the master bathroom.

Wow factor: Cabana apartments
Where: Waterbank at Dakota by UOL Group
What: At this newly launched project, the cabana units, the first of their kind in Singapore, are a row of 11 two-bedroom units built on top of the multi-storey carpark. The units come with an outdoor shower, face a 50m lap pool and have direct access to hot tubs and rain showers on the same deck.

Wow factor: Treehouse apartments
Where: Meadows @ Peirce by UOL
What: Three four-bedroom units on the second floor each comes with an outdoor terrace and a 'treehouse' that is about the size of a bedroom. The spot is great for barbecues and for children to do some camping without having to leave home. All three units have been sold.
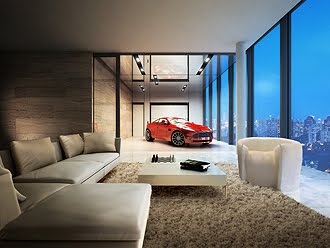
Wow factor: En-suite sky garages
Where: Hamilton Scotts by Hayden Properties
What: Home owners who are so attached to their cars that they cannot bear to leave them in a carpark can now park them next to their living rooms - in their high-rise apartments. The high-end condo in Scotts Road is the first in Asia to have en-suite 'sky garages'.
The parking space, which can fit two cars, is separated from the living area by double-glazed glass. Drivers stop their vehicles at a designated point in the basement, exit and undergo a biometric scan, whereupon a lift transports the car to the correct unit in an automated, driverless process. No need to worry about reversing out the window.
Wow factor: Private lap pools
Where: The Marq On Paterson Hill by SC Global; Nassim Park Residences by UOL; and The Stellar, Elliot at the East Coast and Goodwood Residence by Guocoland

What: Yet another first in Singapore - in this case, every apartment in one tower of The Marq, which was launched in 2007, will have a 15m private lap pool that is cantilevered, giving residents water views coupled with the Orchard Road skyline in the background.
Over at UOL's Nassim Park Residences, which was launched in 2008, the ground-floor units and penthouses come with their own swimming pools. They have all been sold.
Guocoland says its developments' special ground-floor units, which come with private pools, were snapped up quickly.
Wow factor: Dual-key apartments
Where: Caspian at Lakeside, 8@Woodleigh and Flamingo Valley at Siglap, all by Frasers Centrepoint; and Waterbank at Dakota by UOL
What: A smaller unit that is attached to a bigger unit. Each unit comes fully equipped with its own kitchen, bathroom and dining and living areas. They each have their own entrance which opens up to a shared foyer.
With these features, the apartments are great for multi-generational living and for renting.
ST : More say S'pore a great place to live
May 1, 2010
More say S'pore a great place to live
Survey shows rise in satisfaction, sense of belonging
By Joyce Teo
READ blogs and other media and you can get the impression that we are always whining about our lot. Yet, a new survey shows just the opposite - that Singapore is a much-loved home to its people and foreigners with a growing sense of belonging.
In fact the levels of satisfaction are growing, indicating that efforts to remake the place into a more vibrant city are having real effects at ground level.
The latest lifestyle survey by the Urban Redevelopment Authority (URA), out yesterday, asked 4,000 people - mostly Singaporeans but also foreigners and permanent residents - about this place they call home.
It was carried out from August last year to March this year.
More than 80per cent of Singaporeans and permanent residents agreed that this is a great place in which to live, work and play.
This is 10per cent up on satisfaction levels in a 2006 survey - a smaller-scale public perception survey, said National Development Minister Mah Bow Tan.
Foreigners are even keener, with more than 85per cent raising their glasses to Singapore.
Mr Mah told the URA Corporate Plan Seminar yesterday that close to 90per cent of respondents said Singapore was their home and where they belonged, up 20 percentage points from the 2006 survey.
'The survey results are showing a positive trend - that Singaporeans love their city more,' said Mr Mah.
The survey data will be used for the ongoing Concept Plan 2011 review, which maps out Singapore's long-term land use strategies and directions.
'With our new hardware in place, we need to look beyond the physical, to search for the 'soul' of our city, and work towards enhancing it,' added Mr Mah.
Soul is not easy to find, however, as DP Architects director Tai Lee Siang told The Straits Times.
'It requires both the hardware and software working in unison - not one after another. While the skyline and architectural environment (here) are becoming exciting, I can't say that there are many spaces that Singaporeans can occupy and call their own.'
As a start, the Government will put more effort into 'making places', or place management, so that key areas of the city can be activated, Mr Mah said.
This is already happening at Marina Bay and will occur at the Singapore River, Orchard Road, the Bras Basah and Bugis precinct, and historic districts.
The URA will soon call a tender for a consultancy to formulate a five-year plan to work with stakeholders to develop the Singapore River precinct.
Mr Mah identified three key ingredients - the three 'Ps' - that are needed to make a place vibrant and distinctive.
The first is planning for land use, a major concern of Singapore residents, as the URA survey revealed.
They fear the physical landscape changes too fast and that Singapore does not keep enough familiar buildings and places.
The URA has increased the number of conserved buildings and structures from 3,000 or so to about 7,000 over the past two decades but conservation is challenging in a land-scarce nation, said Mr Mah.
'For each potential conservation site, there is a tension between the redevelopment and conservation; it's always a very tough call...'
URA chairman Alan Chan said yesterday: 'In our planning function, we ensure that Singapore's physical development is able to support our population and economic growth in a sustainable manner.'
Mr Mah said the URA will start work in Waterloo Street and Queen Street later this year to make it more pedestrian-friendly and install infrastructure to facilitate street events. About $10million will be spent, with the project finished by early 2012.
Singapore will continue to beef up its hardware but shift focus to the softer aspects of its quality of life, said Mr Mah. This is the second 'P' - programmes.
'What breathes life into a place are the programmes that will in turn, bring in the people,' he said.
'But ultimately, what gives a place its soul is the last 'P', which is people.'
Places only truly come alive when the community uses the spaces to interact and bond, said Mr Mah.
Mr Tai added:'The key to creating a soul is ownership. Singaporeans must feel that they can 'own' the urban spaces in Singapore.'
joyceteo@sph.com.sg
More say S'pore a great place to live
Survey shows rise in satisfaction, sense of belonging
By Joyce Teo
READ blogs and other media and you can get the impression that we are always whining about our lot. Yet, a new survey shows just the opposite - that Singapore is a much-loved home to its people and foreigners with a growing sense of belonging.
In fact the levels of satisfaction are growing, indicating that efforts to remake the place into a more vibrant city are having real effects at ground level.
The latest lifestyle survey by the Urban Redevelopment Authority (URA), out yesterday, asked 4,000 people - mostly Singaporeans but also foreigners and permanent residents - about this place they call home.
It was carried out from August last year to March this year.
More than 80per cent of Singaporeans and permanent residents agreed that this is a great place in which to live, work and play.
This is 10per cent up on satisfaction levels in a 2006 survey - a smaller-scale public perception survey, said National Development Minister Mah Bow Tan.
Foreigners are even keener, with more than 85per cent raising their glasses to Singapore.
Mr Mah told the URA Corporate Plan Seminar yesterday that close to 90per cent of respondents said Singapore was their home and where they belonged, up 20 percentage points from the 2006 survey.
'The survey results are showing a positive trend - that Singaporeans love their city more,' said Mr Mah.
The survey data will be used for the ongoing Concept Plan 2011 review, which maps out Singapore's long-term land use strategies and directions.
'With our new hardware in place, we need to look beyond the physical, to search for the 'soul' of our city, and work towards enhancing it,' added Mr Mah.
Soul is not easy to find, however, as DP Architects director Tai Lee Siang told The Straits Times.
'It requires both the hardware and software working in unison - not one after another. While the skyline and architectural environment (here) are becoming exciting, I can't say that there are many spaces that Singaporeans can occupy and call their own.'
As a start, the Government will put more effort into 'making places', or place management, so that key areas of the city can be activated, Mr Mah said.
This is already happening at Marina Bay and will occur at the Singapore River, Orchard Road, the Bras Basah and Bugis precinct, and historic districts.
The URA will soon call a tender for a consultancy to formulate a five-year plan to work with stakeholders to develop the Singapore River precinct.
Mr Mah identified three key ingredients - the three 'Ps' - that are needed to make a place vibrant and distinctive.
The first is planning for land use, a major concern of Singapore residents, as the URA survey revealed.
They fear the physical landscape changes too fast and that Singapore does not keep enough familiar buildings and places.
The URA has increased the number of conserved buildings and structures from 3,000 or so to about 7,000 over the past two decades but conservation is challenging in a land-scarce nation, said Mr Mah.
'For each potential conservation site, there is a tension between the redevelopment and conservation; it's always a very tough call...'
URA chairman Alan Chan said yesterday: 'In our planning function, we ensure that Singapore's physical development is able to support our population and economic growth in a sustainable manner.'
Mr Mah said the URA will start work in Waterloo Street and Queen Street later this year to make it more pedestrian-friendly and install infrastructure to facilitate street events. About $10million will be spent, with the project finished by early 2012.
Singapore will continue to beef up its hardware but shift focus to the softer aspects of its quality of life, said Mr Mah. This is the second 'P' - programmes.
'What breathes life into a place are the programmes that will in turn, bring in the people,' he said.
'But ultimately, what gives a place its soul is the last 'P', which is people.'
Places only truly come alive when the community uses the spaces to interact and bond, said Mr Mah.
Mr Tai added:'The key to creating a soul is ownership. Singaporeans must feel that they can 'own' the urban spaces in Singapore.'
joyceteo@sph.com.sg
ST : A Great place to live, work and play
May 1, 2010
SINGAPORE:
A Great place to live, work and play
That's the conclusion of the Urban Redevelopment Authority's (URA) latest lifestyle survey that covered 4,000 respondents, including 398 permanent residents and 395 foreigners. They were interviewed from August last year to March this year. Here are some of the findings
Housing
MOST Singapore residents - 72 per cent - prefer to live in public housing, according to the second URA lifestyle survey.
This is in contrast to the first survey done in 2002-2004 when nearly half said they wanted to own private housing.
HDB four-room flats are the best loved housing type, with nearly 28 per cent of respondents opting for it, followed by five-room flats. Three-room flats, private condos and HDB executive flats are also popular.
Housing cost was the most important consideration in terms of the respondents' choice of location, followed by proximity to public transport and neighbourhood facilities.
Said 38-year-old Nathaniel Koh: 'I aspire to own a piece of private property. But given what I can afford, I would buy a three-room flat if I remain single or a resale four-room flat if I get married.'
--------------------------------------------------------------------------------
The Elderly
THEIR TOP 5 WANTS
· Elderly friendly facilities and amenities within walking distance of home.
· Elderly friendly features at home.
· Affordable housing.
· Adequate subsidies.
· Retirement villages with facilities.
ALMOST 80 per cent of older respondents prefer to stay in regular housing rather than retirement villages or flats for the elderly.
They cited cost as the biggest factor influencing their housing choice, followed by access to public transport and proximity to neighbourhood amenities like wet markets and clinics.
'Not only will the rent for private retirement villages be expensive, when you pass away, you won't have a house to leave for your children,' said Madam Chong, 66, on why she preferred living at home. She did not want to give her full name.
Other factors holding the elderly back from moving into retirement villages are the desire to retain a sense of independence, to age in a familiar environment and to encourage inter-generation interaction.
Respondents also wanted elderly friendly facilities to be provided within walking distance from home.
'I want to stay where I am now,' said Mr Tan Chin Huat, 79.
--------------------------------------------------------------------------------
Conservation
WHILE Singapore is seen as an endearing home, about 73 per cent of respondents feel its physical landscape changes too quickly.
They believe that familiar places contribute strongly to their sense of belonging and should be kept at all costs.
Even more striking, 96.6 per cent of respondents feel that hawker centres should be maintained as a key amenity in our housing estates.
These centres as well as local shops are seen as being important to a neighbourhood's identity.
'The hawker centre represents the easy mixing of all races and it gives us character,' said Mr See Chan Teck, 76.
The poll also found that housing estates have left people with the fondest memories, followed by national icons - Sentosa, Changi Airport, the Esplanade and conservation areas. Conservation areas included Chinatown and Boat Quay.
More than 90 per cent of them feel that greenery contributes strongly to the nation's identity, citing East Coast Park, Botanic Gardens and Bishan Park as places that make Singapore special.
--------------------------------------------------------------------------------
Leisure
THE variety and vibrancy of nightlife is leaving 57 per cent of residents less than satisfied. But 51 per cent, mostly the elderly and parents with young children, were neutral on the issue.
To encourage later nights out, those polled cited extending the hours of public transport and entertainment places as the most important factors.
Singapore's leisure environment scored well with 84 per cent saying they were satisfied, while 92 per cent felt Singapore offered activities they like.
The rest cited mostly outdoor activities, such as skiing, hiking, sky diving and bungee jumping, as activities that were lacking.
Business development officer Jacob Lim, 26, said Singapore lacked the buzz of many other world-class cities like Hong Kong and London.
'It's pretty much the same scene over and over again here. There are only that many places, and even Clarke Quay is getting too crowded,' he said.
'Everything seems planned from the top down - even where the nightlife should be - but you can't plan fun in such a manufactured way.'
--------------------------------------------------------------------------------
Transport
THE allure of the city centre as a work place has faded with more people wanting their offices to be closer to home.
The poll found that 66 per cent of respondents wanted to work in their immediate neighbourhood.
Toiling in the city centre came in a distant second at 13 per cent.
The ease of access to work and its proximity to public transport and home were cited as the top three factors influencing choice of employment location.
With 63 per cent of those polled taking public transport to work, respondents also picked cheaper fares and increased frequency of services as ways to encourage a greater use of buses and trains.
Sales coordinator Tay Mei Fong, 47, said she takes about an hour to get to her work place in Havelock Road from Simei, using the train and public bus.
Her views are similar to the 40 per cent of respondents who take more than 30 minutes to get to their place of employment.
It is no surprise that 69 per cent wanted travel times of under 30 minutes.
'I would definitely prefer working close to home as it would reduce my transport costs, allow me to avoid congestion on the road and also allow me to be able to rush home if there are any emergencies,' Madam Tay said.
--------------------------------------------------------------------------------
Foreigners
FOREIGNERS and Singaporeans said watching TV and movies at home is their top leisure activity.
But while going to a pub or club was the second favourite activity for foreigners, it did not make the top five for Singaporeans.
The survey found that 87.3 per cent of foreigners surveyed agreed that Singapore is a great place to live, work and play in.
Eighty-one per cent also agreed that Singapore is a vibrant and exciting city with its own distinctive character.
What they like most about Singapore are its clean and safe environment and the climate. Nearly nine out of 10 respondents said that greenery contributed to Singapore's identity.
Only about 54 per cent of the foreigners said they were satisfied with the night-life offerings, with a significant proportion neutral on this.
Foreigners showed a strong preference for living in the fringe areas or in the city centre, unlike Singaporeans, who showed no strong preference for any particular region.
About 93 per cent of all foreigners rent their homes.
JOYCE TEO, ESTHER TEO & MARISSA LEE
SINGAPORE:
A Great place to live, work and play
That's the conclusion of the Urban Redevelopment Authority's (URA) latest lifestyle survey that covered 4,000 respondents, including 398 permanent residents and 395 foreigners. They were interviewed from August last year to March this year. Here are some of the findings
Housing
MOST Singapore residents - 72 per cent - prefer to live in public housing, according to the second URA lifestyle survey.
This is in contrast to the first survey done in 2002-2004 when nearly half said they wanted to own private housing.
HDB four-room flats are the best loved housing type, with nearly 28 per cent of respondents opting for it, followed by five-room flats. Three-room flats, private condos and HDB executive flats are also popular.
Housing cost was the most important consideration in terms of the respondents' choice of location, followed by proximity to public transport and neighbourhood facilities.
Said 38-year-old Nathaniel Koh: 'I aspire to own a piece of private property. But given what I can afford, I would buy a three-room flat if I remain single or a resale four-room flat if I get married.'
--------------------------------------------------------------------------------
The Elderly
THEIR TOP 5 WANTS
· Elderly friendly facilities and amenities within walking distance of home.
· Elderly friendly features at home.
· Affordable housing.
· Adequate subsidies.
· Retirement villages with facilities.
ALMOST 80 per cent of older respondents prefer to stay in regular housing rather than retirement villages or flats for the elderly.
They cited cost as the biggest factor influencing their housing choice, followed by access to public transport and proximity to neighbourhood amenities like wet markets and clinics.
'Not only will the rent for private retirement villages be expensive, when you pass away, you won't have a house to leave for your children,' said Madam Chong, 66, on why she preferred living at home. She did not want to give her full name.
Other factors holding the elderly back from moving into retirement villages are the desire to retain a sense of independence, to age in a familiar environment and to encourage inter-generation interaction.
Respondents also wanted elderly friendly facilities to be provided within walking distance from home.
'I want to stay where I am now,' said Mr Tan Chin Huat, 79.
--------------------------------------------------------------------------------
Conservation
WHILE Singapore is seen as an endearing home, about 73 per cent of respondents feel its physical landscape changes too quickly.
They believe that familiar places contribute strongly to their sense of belonging and should be kept at all costs.
Even more striking, 96.6 per cent of respondents feel that hawker centres should be maintained as a key amenity in our housing estates.
These centres as well as local shops are seen as being important to a neighbourhood's identity.
'The hawker centre represents the easy mixing of all races and it gives us character,' said Mr See Chan Teck, 76.
The poll also found that housing estates have left people with the fondest memories, followed by national icons - Sentosa, Changi Airport, the Esplanade and conservation areas. Conservation areas included Chinatown and Boat Quay.
More than 90 per cent of them feel that greenery contributes strongly to the nation's identity, citing East Coast Park, Botanic Gardens and Bishan Park as places that make Singapore special.
--------------------------------------------------------------------------------
Leisure
THE variety and vibrancy of nightlife is leaving 57 per cent of residents less than satisfied. But 51 per cent, mostly the elderly and parents with young children, were neutral on the issue.
To encourage later nights out, those polled cited extending the hours of public transport and entertainment places as the most important factors.
Singapore's leisure environment scored well with 84 per cent saying they were satisfied, while 92 per cent felt Singapore offered activities they like.
The rest cited mostly outdoor activities, such as skiing, hiking, sky diving and bungee jumping, as activities that were lacking.
Business development officer Jacob Lim, 26, said Singapore lacked the buzz of many other world-class cities like Hong Kong and London.
'It's pretty much the same scene over and over again here. There are only that many places, and even Clarke Quay is getting too crowded,' he said.
'Everything seems planned from the top down - even where the nightlife should be - but you can't plan fun in such a manufactured way.'
--------------------------------------------------------------------------------
Transport
THE allure of the city centre as a work place has faded with more people wanting their offices to be closer to home.
The poll found that 66 per cent of respondents wanted to work in their immediate neighbourhood.
Toiling in the city centre came in a distant second at 13 per cent.
The ease of access to work and its proximity to public transport and home were cited as the top three factors influencing choice of employment location.
With 63 per cent of those polled taking public transport to work, respondents also picked cheaper fares and increased frequency of services as ways to encourage a greater use of buses and trains.
Sales coordinator Tay Mei Fong, 47, said she takes about an hour to get to her work place in Havelock Road from Simei, using the train and public bus.
Her views are similar to the 40 per cent of respondents who take more than 30 minutes to get to their place of employment.
It is no surprise that 69 per cent wanted travel times of under 30 minutes.
'I would definitely prefer working close to home as it would reduce my transport costs, allow me to avoid congestion on the road and also allow me to be able to rush home if there are any emergencies,' Madam Tay said.
--------------------------------------------------------------------------------
Foreigners
FOREIGNERS and Singaporeans said watching TV and movies at home is their top leisure activity.
But while going to a pub or club was the second favourite activity for foreigners, it did not make the top five for Singaporeans.
The survey found that 87.3 per cent of foreigners surveyed agreed that Singapore is a great place to live, work and play in.
Eighty-one per cent also agreed that Singapore is a vibrant and exciting city with its own distinctive character.
What they like most about Singapore are its clean and safe environment and the climate. Nearly nine out of 10 respondents said that greenery contributed to Singapore's identity.
Only about 54 per cent of the foreigners said they were satisfied with the night-life offerings, with a significant proportion neutral on this.
Foreigners showed a strong preference for living in the fringe areas or in the city centre, unlike Singaporeans, who showed no strong preference for any particular region.
About 93 per cent of all foreigners rent their homes.
JOYCE TEO, ESTHER TEO & MARISSA LEE
ST : Max out your housing loan? Think again
May 1, 2010
Max out your housing loan? Think again
You may end up paying off your mortgage well into your twilight years
By Tan Hui Yee
BURIED in the latest Housing Board (HDB) Sample Household Survey is a startling fact about the financial status of Singapore's older generation: 10.7 per cent of elderly households living in HDB flats, as well as 32.3 per cent of their 'future elderly' counterparts, are still paying off their mortgages.
Between 3 per cent and 5 per cent of these households have problems just meeting their daily expenses.
This is the first time the five-yearly survey has looked into the outstanding mortgages of the elderly, who are aged 65 and above, and 'future elderly', who are aged from 55 to 64.
While the survey's authors note that the number of struggling flat owners is small, 'continuous monitoring is necessary to ensure that the well-being of imminent cohorts of the elderly is not compromised by overspending on their housing purchase'.
It is not clear if these financial stragglers were weighed down by recent recessions or if they are home owners who took on heftier mortgages than they could afford during previous property bubbles. But they warrant a closer look in the light of an International Monetary Fund (IMF) report last week flagging possible property bubbles in Asia.
Housing prices in Singapore, Hong Kong, South Korea and mainland China have recovered quickly from the 2008 to 2009 financial crisis and in some cases, have climbed past 2008 peaks, said the IMF. Anti-speculation measures slowed the increase of private property prices here to 5.6 per cent in the first quarter, and that of resale HDB flats to 2.8 per cent. But they have not stopped climbing. As the IMF notes, many people in Asia 'may have been buying in the expectation of price appreciation, rather than simply for dwelling purposes'.
This belief that prices will continue to rise is strong in Singapore, where the economic outlook is turning rosy. More significantly, it is also underpinned by several assumptions, chief of which is that a growing population and the Republic's land scarcity will nudge prices up. Some believe that property is more stable than various investment instruments as the Government will always intervene to shore up prices.
These assumptions lead some people to spend more on housing than they can afford. Yet none of the assumptions is totally true; all come with caveats.
In the long term, a small land supply will always push property prices but land size is not an insurmountable barrier. Development densities can always be raised to allow more homes to be built on the same plot of land.
Meanwhile, the idea that a booming population will push prices up seems logical but the reality is rather more complex. As economist Kim Kyung-Hwan, a visiting professor at the Singapore Management University, points out: The impact of population - or even income growth - on housing prices depends also on how fast housing supply can keep up. Housing prices can rise even without population growth if there simply are not enough new homes.
And the converse can happen as well. It is possible for real prices to stay level despite an influx of migrants if enough new homes are built. Supply of new private homes all but shrivelled up in the depths of the 2008 to 2009 downturn, creating what housing consultants called pent-up demand, which pushed prices up when new projects appeared.
Supply and demand issues aside, many buyers pledge their faith in property because they think it is a 'safe' investment. With the sub-prime crisis having taken the shine off financial markets, bricks and mortar now seem to be a better store of value.
But that depends on the timeframe. National University of Singapore Associate Professor Yu Shi Ming says property makes sense as a hedge against inflation only over 10 or 20 years. 'People don't plan to hold their property for so long any more,' he says. Within a shorter timeframe, how 'safe' property really is depends on the attitude of buyers.
Fundsupermart general manager Wong Sui Jau states plainly that many do not associate as much risk with property as they should. Property tends to be purchased with loans, and leverage raises the risk of any investment. Someone putting down $200,000 in cash and borrowing $800,000 to buy a $1 million property could stand to lose his entire capital if its value drops by just 20 per cent.
The believer could wait for the market to recover, but he would still have to make monthly loan repayments. Floating interest rates could raise the monthly bill uncomfortably high, especially if he took a bigger loan than he could afford.
At this point, the issue of government intervention comes in. Believers reason that property investment is safe because the Government will always step in to shore up prices to protect people's savings.
It is no secret that HDB flats are stores of retirement savings for many heartlanders. Older flat owners these days can rent out their flat, downgrade to a smaller one or even sell back a remaining lease to finance retirement expenses. The last two options are dependent on the value of the flat: if it drops, their incomes shrink accordingly.
While it makes sense for the Government to keep speculation and volatility in check, it is a stretch to expect significant intervention to shore up prices when economic fundamentals are weak. This is especially so since one of the Government's chief mandates is to keep prices accessible to cater to new home seekers.
It may be hard to imagine in a booming market that what goes up can come down. And believers, after all, are known to be short on memory and long on optimism.
But now, more than ever, would be a good time to redo sums and readjust expectations to avoid overspending on housing. After all, no one wants to be paying off a mortgage late into his 60s.
tanhy@sph.com.sg
Max out your housing loan? Think again
You may end up paying off your mortgage well into your twilight years
By Tan Hui Yee
BURIED in the latest Housing Board (HDB) Sample Household Survey is a startling fact about the financial status of Singapore's older generation: 10.7 per cent of elderly households living in HDB flats, as well as 32.3 per cent of their 'future elderly' counterparts, are still paying off their mortgages.
Between 3 per cent and 5 per cent of these households have problems just meeting their daily expenses.
This is the first time the five-yearly survey has looked into the outstanding mortgages of the elderly, who are aged 65 and above, and 'future elderly', who are aged from 55 to 64.
While the survey's authors note that the number of struggling flat owners is small, 'continuous monitoring is necessary to ensure that the well-being of imminent cohorts of the elderly is not compromised by overspending on their housing purchase'.
It is not clear if these financial stragglers were weighed down by recent recessions or if they are home owners who took on heftier mortgages than they could afford during previous property bubbles. But they warrant a closer look in the light of an International Monetary Fund (IMF) report last week flagging possible property bubbles in Asia.
Housing prices in Singapore, Hong Kong, South Korea and mainland China have recovered quickly from the 2008 to 2009 financial crisis and in some cases, have climbed past 2008 peaks, said the IMF. Anti-speculation measures slowed the increase of private property prices here to 5.6 per cent in the first quarter, and that of resale HDB flats to 2.8 per cent. But they have not stopped climbing. As the IMF notes, many people in Asia 'may have been buying in the expectation of price appreciation, rather than simply for dwelling purposes'.
This belief that prices will continue to rise is strong in Singapore, where the economic outlook is turning rosy. More significantly, it is also underpinned by several assumptions, chief of which is that a growing population and the Republic's land scarcity will nudge prices up. Some believe that property is more stable than various investment instruments as the Government will always intervene to shore up prices.
These assumptions lead some people to spend more on housing than they can afford. Yet none of the assumptions is totally true; all come with caveats.
In the long term, a small land supply will always push property prices but land size is not an insurmountable barrier. Development densities can always be raised to allow more homes to be built on the same plot of land.
Meanwhile, the idea that a booming population will push prices up seems logical but the reality is rather more complex. As economist Kim Kyung-Hwan, a visiting professor at the Singapore Management University, points out: The impact of population - or even income growth - on housing prices depends also on how fast housing supply can keep up. Housing prices can rise even without population growth if there simply are not enough new homes.
And the converse can happen as well. It is possible for real prices to stay level despite an influx of migrants if enough new homes are built. Supply of new private homes all but shrivelled up in the depths of the 2008 to 2009 downturn, creating what housing consultants called pent-up demand, which pushed prices up when new projects appeared.
Supply and demand issues aside, many buyers pledge their faith in property because they think it is a 'safe' investment. With the sub-prime crisis having taken the shine off financial markets, bricks and mortar now seem to be a better store of value.
But that depends on the timeframe. National University of Singapore Associate Professor Yu Shi Ming says property makes sense as a hedge against inflation only over 10 or 20 years. 'People don't plan to hold their property for so long any more,' he says. Within a shorter timeframe, how 'safe' property really is depends on the attitude of buyers.
Fundsupermart general manager Wong Sui Jau states plainly that many do not associate as much risk with property as they should. Property tends to be purchased with loans, and leverage raises the risk of any investment. Someone putting down $200,000 in cash and borrowing $800,000 to buy a $1 million property could stand to lose his entire capital if its value drops by just 20 per cent.
The believer could wait for the market to recover, but he would still have to make monthly loan repayments. Floating interest rates could raise the monthly bill uncomfortably high, especially if he took a bigger loan than he could afford.
At this point, the issue of government intervention comes in. Believers reason that property investment is safe because the Government will always step in to shore up prices to protect people's savings.
It is no secret that HDB flats are stores of retirement savings for many heartlanders. Older flat owners these days can rent out their flat, downgrade to a smaller one or even sell back a remaining lease to finance retirement expenses. The last two options are dependent on the value of the flat: if it drops, their incomes shrink accordingly.
While it makes sense for the Government to keep speculation and volatility in check, it is a stretch to expect significant intervention to shore up prices when economic fundamentals are weak. This is especially so since one of the Government's chief mandates is to keep prices accessible to cater to new home seekers.
It may be hard to imagine in a booming market that what goes up can come down. And believers, after all, are known to be short on memory and long on optimism.
But now, more than ever, would be a good time to redo sums and readjust expectations to avoid overspending on housing. After all, no one wants to be paying off a mortgage late into his 60s.
tanhy@sph.com.sg
BT : Most call S'pore a great place to live, work & play
Business Times - 01 May 2010
Most call S'pore a great place to live, work & play
Two URA surveys find greater satisfaction among residents than in 2006, although many are dismayed by city's rapidly ever-changing face
By UMA SHANKARI
CLOSE to 85 per cent of residents here reckon Singapore is a great place to live, work and play, findings from two recent surveys show.
Most are also attached to their housing estates. But there are areas of concern: the physical landscape in Singapore changes too quickly, and the often-heard complaint that the nightlife scene here is not vibrant enough.
The surveys were conducted by the Urban Redevelopment Authority (URA). It interviewed 4,000 people for its Lifestyle Survey 2009 over seven months from last August to March this year. And it invited the public to give feedback via the Concept Plan 2011 online survey from January to February.
Information gathered from the surveys will be incorporated into the ongoing Concept Plan 2011 review, which maps out the long-term directions for Singapore's land use.
Overall, 83.8 per cent of respondents agreed that Singapore has a great live-work-play environment - a 10.2 per cent increase from what a similar survey found in 2006.
The latest surveys also reveal that more people find Singapore a vibrant and exciting city with its own distinctive character. Seventy-eight per cent of respondents agreed with this - an 11.4 per cent increase from the 2006 survey.
But 73.2 per cent also said they feel the physical landscape here changes too quickly. And 64.2 per cent said Singapore does not keep enough familiar buildings and places around. There was broad agreement that the government should keep enough familiar buildings and places at all cost to strengthen people's sense of belonging.
This is especially so as residents seem to be attached to places. For instance, 34.1 per cent of respondents said they have the fondest memories of housing estates.
On another front, just 43.2 per cent of respondents said they are satisfied or very satisfied with the adequacy, variety and vibrancy of night-time activities and events.
Presenting the findings at a URA seminar yesterday, National Development Minister Mah Bow Tan said they indicate that efforts to remake Singapore are having positive results.
But he said: 'A house is not a home. Simply having a good living environment and First World infrastructure will not create an endearing home. The character of a city - what makes it stand out among many new cities - goes beyond new buildings or iconic structures.'
Mr Mah also gave an update on the government's 'place management' efforts. Place management - now being done for Marina Bay - involves a coordinated, area-based, multi-stakeholder approach that involves the public and private sectors.
Next up is the Singapore River precinct. URA will engage the stakeholders to develop a five-year business plan to increase the area's economic and social vibrancy.
Mr Mah said: 'This could involve working with stakeholders to improve the infrastructure of the area, how they can host events to attract people to the precinct to develop the Singapore River into a vibrant riverfront for all.'
A tender for a business consultancy study on the Singapore River area will be called in May or June.
Place management efforts will also be applied to Orchard Road, Bras Basah, Bugis and historic districts, URA said.
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.

MORE BUZZ
URA will engage stakeholders to develop a five-year business plan to increase the Singapore River area's economic and social vibrancy
Most call S'pore a great place to live, work & play
Two URA surveys find greater satisfaction among residents than in 2006, although many are dismayed by city's rapidly ever-changing face
By UMA SHANKARI
CLOSE to 85 per cent of residents here reckon Singapore is a great place to live, work and play, findings from two recent surveys show.
Most are also attached to their housing estates. But there are areas of concern: the physical landscape in Singapore changes too quickly, and the often-heard complaint that the nightlife scene here is not vibrant enough.
The surveys were conducted by the Urban Redevelopment Authority (URA). It interviewed 4,000 people for its Lifestyle Survey 2009 over seven months from last August to March this year. And it invited the public to give feedback via the Concept Plan 2011 online survey from January to February.
Information gathered from the surveys will be incorporated into the ongoing Concept Plan 2011 review, which maps out the long-term directions for Singapore's land use.
Overall, 83.8 per cent of respondents agreed that Singapore has a great live-work-play environment - a 10.2 per cent increase from what a similar survey found in 2006.
The latest surveys also reveal that more people find Singapore a vibrant and exciting city with its own distinctive character. Seventy-eight per cent of respondents agreed with this - an 11.4 per cent increase from the 2006 survey.
But 73.2 per cent also said they feel the physical landscape here changes too quickly. And 64.2 per cent said Singapore does not keep enough familiar buildings and places around. There was broad agreement that the government should keep enough familiar buildings and places at all cost to strengthen people's sense of belonging.
This is especially so as residents seem to be attached to places. For instance, 34.1 per cent of respondents said they have the fondest memories of housing estates.
On another front, just 43.2 per cent of respondents said they are satisfied or very satisfied with the adequacy, variety and vibrancy of night-time activities and events.
Presenting the findings at a URA seminar yesterday, National Development Minister Mah Bow Tan said they indicate that efforts to remake Singapore are having positive results.
But he said: 'A house is not a home. Simply having a good living environment and First World infrastructure will not create an endearing home. The character of a city - what makes it stand out among many new cities - goes beyond new buildings or iconic structures.'
Mr Mah also gave an update on the government's 'place management' efforts. Place management - now being done for Marina Bay - involves a coordinated, area-based, multi-stakeholder approach that involves the public and private sectors.
Next up is the Singapore River precinct. URA will engage the stakeholders to develop a five-year business plan to increase the area's economic and social vibrancy.
Mr Mah said: 'This could involve working with stakeholders to improve the infrastructure of the area, how they can host events to attract people to the precinct to develop the Singapore River into a vibrant riverfront for all.'
A tender for a business consultancy study on the Singapore River area will be called in May or June.
Place management efforts will also be applied to Orchard Road, Bras Basah, Bugis and historic districts, URA said.
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.

MORE BUZZ
URA will engage stakeholders to develop a five-year business plan to increase the Singapore River area's economic and social vibrancy
Thursday, April 29, 2010
BT : High demand for US home loans but refinancing falls
Business Times - 29 Apr 2010
High demand for US home loans but refinancing falls
(NEW YORK) US mortgage applications fell last week as a drop in home refinancing volume outweighed the highest demand for home purchase loans in six months, data from an industry group showed yesterday.
A modest rise in mortgage rates weighed on demand for home refinancing loans, while the imminent expiration of federal home buyer tax credits likely drove consumers to lock in rates, which remain historically low and are widely expected to move higher as the economy recovers.
The Mortgage Bankers Association said that its seasonally adjusted index of mortgage applications, which includes both purchase and refinance loans, decreased 2.9 per cent for the week ended April 23.
The four-week moving average of mortgage applications, which smooths the volatile weekly figures, was down 3.1 per cent.
The MBA's seasonally adjusted purchase index, a tentative early indicator of home sales, increased 7.4 per cent, reaching its highest level since the week ended Oct 16.
'Purchase activity continues to increase as we approach the end of the homebuyer tax credit programme,' Michael Fratantoni, MBA's vice-president of research and economics, said in a statement.
'Purchase applications were up almost 9 per cent from a month ago, with a disproportionate share of the increase due to government purchase applications. Government applications for purchasing a home accounted for almost 49 per cent of all purchase applications last week,' he said.
To qualify for tax credits of US$8,000 for first-time home buyers and US$6,500 for home owners buying a new residence, eligible borrowers must sign contracts by April 30 and close loans by June 30.
Recent data on sales of new and existing home sales indicate a strong benefit from the tax credits. Government data showed sales of newly built US single-family homes touched their highest level in eight months in March, while industry data showed sales of previously owned homes also gained in March.
James Mallozzi, chairman and chief executive officer of Prudential Real Estate and Relocation Services, said that while home buyer tax credits have helped both first-time home buyers and the US housing market overall, their expiration should not deter home purchasing activity.
'When it comes to home sales, the absolute level of home prices ranks first in importance, the level of mortgage rates ranks second, while the home buyer tax credits ranks a distant third,' he said.
The MBA said that borrowing costs on 30-year fixed-rate mortgages, excluding fees, averaged 5.08 per cent, up 0.04 percentage point from the previous week. Interest rates were also above the year-ago level of 4.62 per cent. An all-time low of 4.61 per cent was set in the week ended March 27, 2009, based on a survey that dates to 1990.
Mortgage rates could head towards 5.50 per cent or 6 per cent later this year, Mr Mallozzi said.
'This could dampen demand and I foresee a slow housing recovery,' he said.
The MBA said that fixed 15-year mortgage rates averaged 4.38 per cent, up from 4.34 per cent the previous week. Rates on one-year adjustable-rate mortgages, or ARMs, increased to 7.03 per cent from 6.95 per cent\. \-- Reuters
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.
High demand for US home loans but refinancing falls
(NEW YORK) US mortgage applications fell last week as a drop in home refinancing volume outweighed the highest demand for home purchase loans in six months, data from an industry group showed yesterday.
A modest rise in mortgage rates weighed on demand for home refinancing loans, while the imminent expiration of federal home buyer tax credits likely drove consumers to lock in rates, which remain historically low and are widely expected to move higher as the economy recovers.
The Mortgage Bankers Association said that its seasonally adjusted index of mortgage applications, which includes both purchase and refinance loans, decreased 2.9 per cent for the week ended April 23.
The four-week moving average of mortgage applications, which smooths the volatile weekly figures, was down 3.1 per cent.
The MBA's seasonally adjusted purchase index, a tentative early indicator of home sales, increased 7.4 per cent, reaching its highest level since the week ended Oct 16.
'Purchase activity continues to increase as we approach the end of the homebuyer tax credit programme,' Michael Fratantoni, MBA's vice-president of research and economics, said in a statement.
'Purchase applications were up almost 9 per cent from a month ago, with a disproportionate share of the increase due to government purchase applications. Government applications for purchasing a home accounted for almost 49 per cent of all purchase applications last week,' he said.
To qualify for tax credits of US$8,000 for first-time home buyers and US$6,500 for home owners buying a new residence, eligible borrowers must sign contracts by April 30 and close loans by June 30.
Recent data on sales of new and existing home sales indicate a strong benefit from the tax credits. Government data showed sales of newly built US single-family homes touched their highest level in eight months in March, while industry data showed sales of previously owned homes also gained in March.
James Mallozzi, chairman and chief executive officer of Prudential Real Estate and Relocation Services, said that while home buyer tax credits have helped both first-time home buyers and the US housing market overall, their expiration should not deter home purchasing activity.
'When it comes to home sales, the absolute level of home prices ranks first in importance, the level of mortgage rates ranks second, while the home buyer tax credits ranks a distant third,' he said.
The MBA said that borrowing costs on 30-year fixed-rate mortgages, excluding fees, averaged 5.08 per cent, up 0.04 percentage point from the previous week. Interest rates were also above the year-ago level of 4.62 per cent. An all-time low of 4.61 per cent was set in the week ended March 27, 2009, based on a survey that dates to 1990.
Mortgage rates could head towards 5.50 per cent or 6 per cent later this year, Mr Mallozzi said.
'This could dampen demand and I foresee a slow housing recovery,' he said.
The MBA said that fixed 15-year mortgage rates averaged 4.38 per cent, up from 4.34 per cent the previous week. Rates on one-year adjustable-rate mortgages, or ARMs, increased to 7.03 per cent from 6.95 per cent\. \-- Reuters
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.
BT : Sitting on a pot of 'collective' gold
Business Times - 29 Apr 2010
Sitting on a pot of 'collective' gold
Developers who snagged en bloc sites earlier have reason to smile
By KALPANA RASHIWALA
(SINGAPORE) While the market mulls over the impact that rule changes will have on collective sales, the spotlight has fallen on developers sitting on prime sites acquired during the previous en bloc boom in 2006-2007.
If the proposed changes make it tougher for prime freehold residential sites to make their way to the market, that will be good news to developers who are already holding such sites acquired earlier.
A compilation by property consultant CB Richard Ellis shows that developers currently have 26 sites in prime districts 9, 10 and 11 snapped up in collective sales in 2006 and 2007 where new projects are still to be launched.
These sites are planned for redevelopment into nearly 4,300 new homes. Outside the prime districts, developers could build a further 4,700 homes on 16 sites purchased through collective sales in 2006-2007
CapitaLand, City Developments Ltd (CDL), Wing Tai, GuocoLand and Overseas Union Enterprise are among the developers who bought prime district en bloc sale plots earlier. For instance, CapitaLand, together with its partners, acquired the Farrer Court plot and is planning a 1,715-unit redevelopment project. Hong Leong Group (including CDL) has exposure to six sites slated for development into over 600 units in locations like Leonie Hill, Anderson and Thomson roads.
These sites and projects will become more precious to developers and they will want to time their launch more judiciously if it gets tougher to replenish landbank in this segment through en bloc sales, say industry observers.
CB Richard Ellis executive director Jeremy Lake says: 'The proposed amendments are unlikely to facilitate the en bloc process significantly and as such, the number of collective sales coming to the market is likely to remain relatively limited.
'From a developer's point of view, it will be more difficult to replace landbank in prime areas so those who have such sites may think more carefully about the timing of launch of new projects on these sites as it will not be easy to find replacement land.'
Giving a more pessimistic take, a developer said: 'I don't think anyone would be too far wrong to say that en bloc sales are just about the only source of supply for prime district freehold sites. The proposed amendments to the Land Titles (Strata) Act will put the 'last nail in the coffin' for en bloc sales in the near future, and the market will be completely dried up for freehold District 9, 10, 11 land supply.'
This will create upward pressure on land prices, he added.
Putting things in perspective, DTZ senior director (investment sales) Shaun Poh says: 'En bloc sales in many developments have already been activated and these are unlikely to be affected by the proposed amendments. The supply from this source should be enough for the market for the time being.
'However, the future pipeline of en bloc sales will be affected.'
On Monday, the Ministry of Law released proposed amendments that will among other things make it harder to restart a collective sale within two years of a failed attempt. Any attempts to convene EGMs to appoint a sales committee during this period will require higher requisition levels from owners - 50 per cent by share value or total number of owners for the first re-try and 80 per cent for any subsequent attempts.
'Already it's not easy to secure requisitions for EGMs based on existing thresholds of 20 per cent by share value or 25 per cent of number of owners,' says DTZ's Mr Poh.
'Now that they're proposing to raise the threshold for restarting previously failed en bloc attempts, it's going to be more difficult for those who want to have another shot when, say, the market suddenly turns hot.'
On a more positive note, Credo Real Estate managing director Karamjit Singh notes that the instances of failed attempts that will be affected by the two-year restriction do not cover cases where owners' 80 or 90 per cent majority consent was secured but the Collective Sales Agreement (CSA) expired because a buyer could not be found in time.
'The projects that may be affected are likely to be those that had attempted an en bloc sale when they should not have, either owing to the project not being fundamentally 'enblocable' or the market was not on their side to an extent that the majority owners rejected the proposal,' he said.
MinLaw hopes its proposal will discourage repeated attempts at en bloc sales where there isn't enough support from owners.
Industry players lauded MinLaw's proposal to streamline the number of EGMs, which should speed up the process. 'We expect to see further en-bloc activity this year,' said Chris Fossick, managing director Singapore and South East Asia for Jones Lang LaSalle.
Others, however, complain that the the ministry is not doing anything to mitigate bottlenecks caused by the need to have lawyers witness signing of the CSA.
This has also jacked up legal costs. Some have suggested doing away with this requirement since those who sign are given a five-day cooling-off period.
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.

Hot asset: Developers of prime sites like Farrer Court (above) will time their project launches more carefully
Sitting on a pot of 'collective' gold
Developers who snagged en bloc sites earlier have reason to smile
By KALPANA RASHIWALA
(SINGAPORE) While the market mulls over the impact that rule changes will have on collective sales, the spotlight has fallen on developers sitting on prime sites acquired during the previous en bloc boom in 2006-2007.
If the proposed changes make it tougher for prime freehold residential sites to make their way to the market, that will be good news to developers who are already holding such sites acquired earlier.
A compilation by property consultant CB Richard Ellis shows that developers currently have 26 sites in prime districts 9, 10 and 11 snapped up in collective sales in 2006 and 2007 where new projects are still to be launched.
These sites are planned for redevelopment into nearly 4,300 new homes. Outside the prime districts, developers could build a further 4,700 homes on 16 sites purchased through collective sales in 2006-2007
CapitaLand, City Developments Ltd (CDL), Wing Tai, GuocoLand and Overseas Union Enterprise are among the developers who bought prime district en bloc sale plots earlier. For instance, CapitaLand, together with its partners, acquired the Farrer Court plot and is planning a 1,715-unit redevelopment project. Hong Leong Group (including CDL) has exposure to six sites slated for development into over 600 units in locations like Leonie Hill, Anderson and Thomson roads.
These sites and projects will become more precious to developers and they will want to time their launch more judiciously if it gets tougher to replenish landbank in this segment through en bloc sales, say industry observers.
CB Richard Ellis executive director Jeremy Lake says: 'The proposed amendments are unlikely to facilitate the en bloc process significantly and as such, the number of collective sales coming to the market is likely to remain relatively limited.
'From a developer's point of view, it will be more difficult to replace landbank in prime areas so those who have such sites may think more carefully about the timing of launch of new projects on these sites as it will not be easy to find replacement land.'
Giving a more pessimistic take, a developer said: 'I don't think anyone would be too far wrong to say that en bloc sales are just about the only source of supply for prime district freehold sites. The proposed amendments to the Land Titles (Strata) Act will put the 'last nail in the coffin' for en bloc sales in the near future, and the market will be completely dried up for freehold District 9, 10, 11 land supply.'
This will create upward pressure on land prices, he added.
Putting things in perspective, DTZ senior director (investment sales) Shaun Poh says: 'En bloc sales in many developments have already been activated and these are unlikely to be affected by the proposed amendments. The supply from this source should be enough for the market for the time being.
'However, the future pipeline of en bloc sales will be affected.'
On Monday, the Ministry of Law released proposed amendments that will among other things make it harder to restart a collective sale within two years of a failed attempt. Any attempts to convene EGMs to appoint a sales committee during this period will require higher requisition levels from owners - 50 per cent by share value or total number of owners for the first re-try and 80 per cent for any subsequent attempts.
'Already it's not easy to secure requisitions for EGMs based on existing thresholds of 20 per cent by share value or 25 per cent of number of owners,' says DTZ's Mr Poh.
'Now that they're proposing to raise the threshold for restarting previously failed en bloc attempts, it's going to be more difficult for those who want to have another shot when, say, the market suddenly turns hot.'
On a more positive note, Credo Real Estate managing director Karamjit Singh notes that the instances of failed attempts that will be affected by the two-year restriction do not cover cases where owners' 80 or 90 per cent majority consent was secured but the Collective Sales Agreement (CSA) expired because a buyer could not be found in time.
'The projects that may be affected are likely to be those that had attempted an en bloc sale when they should not have, either owing to the project not being fundamentally 'enblocable' or the market was not on their side to an extent that the majority owners rejected the proposal,' he said.
MinLaw hopes its proposal will discourage repeated attempts at en bloc sales where there isn't enough support from owners.
Industry players lauded MinLaw's proposal to streamline the number of EGMs, which should speed up the process. 'We expect to see further en-bloc activity this year,' said Chris Fossick, managing director Singapore and South East Asia for Jones Lang LaSalle.
Others, however, complain that the the ministry is not doing anything to mitigate bottlenecks caused by the need to have lawyers witness signing of the CSA.
This has also jacked up legal costs. Some have suggested doing away with this requirement since those who sign are given a five-day cooling-off period.
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.

Hot asset: Developers of prime sites like Farrer Court (above) will time their project launches more carefully
TODAY ONLINE : Office market is 'bottoming out'
Office market is 'bottoming out'
Raffles Place not losing lustre yet, says CCT's CEO
05:55 AM Apr 29, 2010
SINGAPORE - Raffles Place is not likely to lose its lustre as a business district, said Ms Lynette Leong, chief executive officer of CapitaCommercial Trust (CCT), which has three office properties in the area.
Despite some financial institutions moving to Marina Bay, she is seeing interest from existing tenants and potential tenants for more office space in the Trust's Raffles Place properties, which include One George Street, HSBC Building and Six Battery Road.
"We believe the enlargement of the Central Business District by the extension of its boundaries ... to encompass Marina Bay is well planned to meet this anticipated growing office demand," said Ms Leong.
CCT, which held its AGM yesterday, assured the 230-odd unitholders present that the office market is bottoming out and CCT intends to ride the upside of the recovery through its "well-located properties and financial flexibility".
"If the property has reached an optimal stage of its life cycle, then we will divest the asset and reinvest the sale proceeds into assets which have got better potential for upside," said Ms Leong of CCT's portfolio reconstitution strategy.
Under this strategy, CCT recently sold one of its assets, Robinson Point, to a private fund run by AEW Asia for $203.25 million.
Besides its properties in Raffles Place, CCT also counts Wilkie Edge, Bugis Village, Starhub Centre, Raffles City, Golden Shoe Car Park, Market Street Car Park and Capital Tower in its Singapore portfolio.
However, Ms Leong said with 4.5 million sq ft of office space coming on stream in the next two years, there was uncertainty clouding the recovery of office rentals.
CCT also told unitholders that as of the end of last month, the trust had tenants committed to renew close to 8 per cent of the leases due, leaving a balance of about 16 per cent of leases unrenewed. Distribution per unit for Q1 rose to 1.93 cents per unit from 1.62 cents in the corresponding period last year.
Copyright 2010 MediaCorp Pte Ltd | All Rights Reserved
Raffles Place not losing lustre yet, says CCT's CEO
05:55 AM Apr 29, 2010
SINGAPORE - Raffles Place is not likely to lose its lustre as a business district, said Ms Lynette Leong, chief executive officer of CapitaCommercial Trust (CCT), which has three office properties in the area.
Despite some financial institutions moving to Marina Bay, she is seeing interest from existing tenants and potential tenants for more office space in the Trust's Raffles Place properties, which include One George Street, HSBC Building and Six Battery Road.
"We believe the enlargement of the Central Business District by the extension of its boundaries ... to encompass Marina Bay is well planned to meet this anticipated growing office demand," said Ms Leong.
CCT, which held its AGM yesterday, assured the 230-odd unitholders present that the office market is bottoming out and CCT intends to ride the upside of the recovery through its "well-located properties and financial flexibility".
"If the property has reached an optimal stage of its life cycle, then we will divest the asset and reinvest the sale proceeds into assets which have got better potential for upside," said Ms Leong of CCT's portfolio reconstitution strategy.
Under this strategy, CCT recently sold one of its assets, Robinson Point, to a private fund run by AEW Asia for $203.25 million.
Besides its properties in Raffles Place, CCT also counts Wilkie Edge, Bugis Village, Starhub Centre, Raffles City, Golden Shoe Car Park, Market Street Car Park and Capital Tower in its Singapore portfolio.
However, Ms Leong said with 4.5 million sq ft of office space coming on stream in the next two years, there was uncertainty clouding the recovery of office rentals.
CCT also told unitholders that as of the end of last month, the trust had tenants committed to renew close to 8 per cent of the leases due, leaving a balance of about 16 per cent of leases unrenewed. Distribution per unit for Q1 rose to 1.93 cents per unit from 1.62 cents in the corresponding period last year.
Copyright 2010 MediaCorp Pte Ltd | All Rights Reserved
TODAY ONLINE: Two prime freehold commercial sites up for public tender
Two prime freehold commercial sites up for public tender
05:55 AM Apr 29, 2010
SINGAPORE - The red-hot property market has prompted the sale of two prime freehold commercial buildings.
One is a four-storey building at 23 and 25 Kampong Bahru Road, opposite the Singapore General Hospital. The price is $16 million, or $1,421 per square foot of gross floor area. The site area is about 3,402 sq ft, with a total strata area of some 11,259 sq ft.
The boutique building has been set aside for commercial use, but the vendor is seeking approval to convert it to hotel use.
Another building up for sale is another four-storey building at 213 Upper Thomson Road. It is set amid an established, affluent private residential enclave near the Singapore Island Country Club.
The asking price for the building is $5.5 million, which works out to $823 per square foot of gross floor area. This building has a site area of approximately 2,446 sq ft and a gross floor area of about 6,679 sq ft.
The proposed developments for the property are corporate offices, showroom space and F&B businesses.
CB Richard Ellis is the marketing agent for this public tender, which closes on May 20. Ephraim Seow
Copyright 2010 MediaCorp Pte Ltd | All Rights Reserved
05:55 AM Apr 29, 2010
SINGAPORE - The red-hot property market has prompted the sale of two prime freehold commercial buildings.
One is a four-storey building at 23 and 25 Kampong Bahru Road, opposite the Singapore General Hospital. The price is $16 million, or $1,421 per square foot of gross floor area. The site area is about 3,402 sq ft, with a total strata area of some 11,259 sq ft.
The boutique building has been set aside for commercial use, but the vendor is seeking approval to convert it to hotel use.
Another building up for sale is another four-storey building at 213 Upper Thomson Road. It is set amid an established, affluent private residential enclave near the Singapore Island Country Club.
The asking price for the building is $5.5 million, which works out to $823 per square foot of gross floor area. This building has a site area of approximately 2,446 sq ft and a gross floor area of about 6,679 sq ft.
The proposed developments for the property are corporate offices, showroom space and F&B businesses.
CB Richard Ellis is the marketing agent for this public tender, which closes on May 20. Ephraim Seow
Copyright 2010 MediaCorp Pte Ltd | All Rights Reserved
ST : Bid too high, so Beijing cancels land auction
Apr 29, 2010
Bid too high, so Beijing cancels land auction
BEIJING: A land auction in Beijing was cancelled after bidding exceeded a price ceiling set for the lot, as the Chinese government expands efforts to rein in the nation's property market.
The highest price bid for the Beijing lot, zoned for residential development, at the auction on Monday was 4,718 yuan (S$950) per sq m, exceeding the 4,700 yuan per sq m limit set by the government, the Ministry of Land and Resources said on its website yesterday.
The ministry's Beijing branch said it began setting limits on the price of land this month on a trial basis.
'Imagine a seller refuses your business because he thinks you are paying too much for his products,' Bank of America-Merrill Lynch analysts wrote in a report distributed yesterday.
'It demonstrates the type of pressure the central government is putting on local officials to get the property market right this time; this increases the risk of potential overshooting in the property market crackdown.'
China began requiring developers to pay higher deposits for land purchases last month, and banned banks from lending to developers found to be hoarding land, as Premier Wen Jiabao pledged to crack down on real estate speculation and keep housing affordable.
Property prices in 70 Chinese cities gained a record 11.7 per cent last month compared with prices a year earlier.
The average price of land in 105 Chinese cities rose 8.1 per cent in the first quarter from the price a year earlier, to 2,700 yuan per sq m.
The ministry's Beijing branch this month began limiting how much land developers may buy.
Videos will also be taken of land auctions, notary personnel will observe the bidding, and contracts between Beijing's land bureau and developers for purchases of lots will be made public, according to the statement.
China's property stocks have plunged 20 per cent this year, making them the worst performers among
major industry groups after Beijing began clamping down on the property market.
China will place a moratorium on capital raising by real estate firms as part of a broader campaign to rein in property price rises, state media reported yesterday.
The move could stand in the way of about 110 billion yuan in share issues planned by 45 companies, unnamed sources close to the China Securities Regulatory Commission told the China Daily.
The suspension will allow the Ministry of Land and Resources to examine whether companies have used illegal methods to manipulate market prices, the newspaper said.
BLOOMBERG, REUTERS
Bid too high, so Beijing cancels land auction
BEIJING: A land auction in Beijing was cancelled after bidding exceeded a price ceiling set for the lot, as the Chinese government expands efforts to rein in the nation's property market.
The highest price bid for the Beijing lot, zoned for residential development, at the auction on Monday was 4,718 yuan (S$950) per sq m, exceeding the 4,700 yuan per sq m limit set by the government, the Ministry of Land and Resources said on its website yesterday.
The ministry's Beijing branch said it began setting limits on the price of land this month on a trial basis.
'Imagine a seller refuses your business because he thinks you are paying too much for his products,' Bank of America-Merrill Lynch analysts wrote in a report distributed yesterday.
'It demonstrates the type of pressure the central government is putting on local officials to get the property market right this time; this increases the risk of potential overshooting in the property market crackdown.'
China began requiring developers to pay higher deposits for land purchases last month, and banned banks from lending to developers found to be hoarding land, as Premier Wen Jiabao pledged to crack down on real estate speculation and keep housing affordable.
Property prices in 70 Chinese cities gained a record 11.7 per cent last month compared with prices a year earlier.
The average price of land in 105 Chinese cities rose 8.1 per cent in the first quarter from the price a year earlier, to 2,700 yuan per sq m.
The ministry's Beijing branch this month began limiting how much land developers may buy.
Videos will also be taken of land auctions, notary personnel will observe the bidding, and contracts between Beijing's land bureau and developers for purchases of lots will be made public, according to the statement.
China's property stocks have plunged 20 per cent this year, making them the worst performers among
major industry groups after Beijing began clamping down on the property market.
China will place a moratorium on capital raising by real estate firms as part of a broader campaign to rein in property price rises, state media reported yesterday.
The move could stand in the way of about 110 billion yuan in share issues planned by 45 companies, unnamed sources close to the China Securities Regulatory Commission told the China Daily.
The suspension will allow the Ministry of Land and Resources to examine whether companies have used illegal methods to manipulate market prices, the newspaper said.
BLOOMBERG, REUTERS
BT : Beijing land sale scrapped as bid tops set ceiling
Business Times - 29 Apr 2010
Beijing land sale scrapped as bid tops set ceiling
(SHANGHAI) An auction of land in Beijing was cancelled after bidding exceeded a price ceiling set for the lot as the Chinese government expands efforts to rein in the nation's property market.
The highest price bid for the Beijing lot, zoned for residential development, at the auction on Monday was 4,718 yuan (S$945) per square metre, exceeding the 4,700 yuan per square metre limit set by the government, the Ministry of Land and Resources said on its website yesterday.
The ministry's Beijing branch said it began setting limits on the price of land this month on a trial basis.
'Imagine a seller refuses your business because he thinks you are paying too much for his products?' Bank of America-Merrill Lynch analysts led by David Cui wrote in a report distributed yesterday. 'It demonstrates the type of pressure the central government is putting on local officials to get the property market right this time; this increases the risk of potential overshooting in the property market crackdown.'
China began requiring developers pay higher deposits for land purchases last month and banned banks from lending to developers found to be hoarding land as Premier Wen Jiabao pledged to crack down on real-estate speculation and keep housing affordable. Property prices in 70 Chinese cities gained a record 11.7 per cent in March from a year earlier.
The Beijing branch of the land ministry this month began limiting how much land developers may buy, according to a statement posted to its website on April 21. Video will also be taken of land auctions, notary personnel will observe the bidding, and contracts between Beijing's land bureau and developers for purchases of lots will be made public, according to the statement.
Separately, the land ministry's Shanghai bureau said on Tuesday it had postponed the auctioning of four land plots previously scheduled for yesterday to May 7, citing a 'technical hitch.' The average price of land in 105 Chinese cities rose 8.1 per cent in the first quarter from a year earlier to 2,700 yuan per square metre, Minister of Land and Resources Xu Shaoshi said last week.
China's property stocks have plunged 20 per cent this year, making them the worst performers among major industry groups. China Vanke, the nation's biggest publicly traded developer, has fallen 28 per cent this year compared with a 12 per cent drop in the benchmark Shanghai Composite Index.
Regulators have halted share sales by property developers to give the Ministry of Land and Resources the chance to investigate if companies manipulated market prices, the China Daily reported yesterday, citing an unidentified source close to the China Securities Regulatory Commission.
Beijing will be issuing policies limiting how many homes residents of the city are allowed to buy, the Shanghai Securities News reported yesterday. The city will also 'basically' stop loans for the purchase of third homes. - Bloomberg
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.
Beijing land sale scrapped as bid tops set ceiling
(SHANGHAI) An auction of land in Beijing was cancelled after bidding exceeded a price ceiling set for the lot as the Chinese government expands efforts to rein in the nation's property market.
The highest price bid for the Beijing lot, zoned for residential development, at the auction on Monday was 4,718 yuan (S$945) per square metre, exceeding the 4,700 yuan per square metre limit set by the government, the Ministry of Land and Resources said on its website yesterday.
The ministry's Beijing branch said it began setting limits on the price of land this month on a trial basis.
'Imagine a seller refuses your business because he thinks you are paying too much for his products?' Bank of America-Merrill Lynch analysts led by David Cui wrote in a report distributed yesterday. 'It demonstrates the type of pressure the central government is putting on local officials to get the property market right this time; this increases the risk of potential overshooting in the property market crackdown.'
China began requiring developers pay higher deposits for land purchases last month and banned banks from lending to developers found to be hoarding land as Premier Wen Jiabao pledged to crack down on real-estate speculation and keep housing affordable. Property prices in 70 Chinese cities gained a record 11.7 per cent in March from a year earlier.
The Beijing branch of the land ministry this month began limiting how much land developers may buy, according to a statement posted to its website on April 21. Video will also be taken of land auctions, notary personnel will observe the bidding, and contracts between Beijing's land bureau and developers for purchases of lots will be made public, according to the statement.
Separately, the land ministry's Shanghai bureau said on Tuesday it had postponed the auctioning of four land plots previously scheduled for yesterday to May 7, citing a 'technical hitch.' The average price of land in 105 Chinese cities rose 8.1 per cent in the first quarter from a year earlier to 2,700 yuan per square metre, Minister of Land and Resources Xu Shaoshi said last week.
China's property stocks have plunged 20 per cent this year, making them the worst performers among major industry groups. China Vanke, the nation's biggest publicly traded developer, has fallen 28 per cent this year compared with a 12 per cent drop in the benchmark Shanghai Composite Index.
Regulators have halted share sales by property developers to give the Ministry of Land and Resources the chance to investigate if companies manipulated market prices, the China Daily reported yesterday, citing an unidentified source close to the China Securities Regulatory Commission.
Beijing will be issuing policies limiting how many homes residents of the city are allowed to buy, the Shanghai Securities News reported yesterday. The city will also 'basically' stop loans for the purchase of third homes. - Bloomberg
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.
BT : Non-central home prices outpace prime areas
Business Times - 29 Apr 2010
Non-central home prices outpace prime areas
NUS index shows they climbed 1.2% in March while central region home prices dipped
By UMA SHANKARI
(SINGAPORE) Prices of non-landed private homes outside Singapore's prime districts are now growing at a faster rate than prices in the prime districts, according to a new index compiled by the National University of Singapore (NUS).
Flash estimates for March released yesterday show that 'non-central' home prices climbed 1.2 per cent last month, taking the first-quarter rise to 4.4 per cent.
In contrast, prices in the central region - postal districts 1-4 and 9-11 - dipped 0.07 per cent in March. For Q1, they rose 1.7 per cent.
NUS's Singapore Residential Price Index also shows that overall home prices rose 0.3 per cent last month and 2.8 per cent in Q1.
This puts the overall current value of the index just 0.1 per cent below the peak in November 2007. Prices in the central region are now 9.3 per cent below that peak, while prices in non-central areas are 6.4 per cent above the previous peak in January 2008.
'The rate of price growth in the central area has slowed, but for the non-central region, we have not seen an obvious decline in the rate of growth yet,' said Associate Professor Lum Sau Kim, who leads the group that compiles the index.
In 2009, price growth in the central region outpaced that in non-central areas. Home prices grew 27.3 per cent in the central region and 19.5 per cent in non-central areas. The overall index rose 22.2 per cent.
Analysts say that the moderation in the growth of prices - seen in both the NUS index and official Urban Redevelopment Authority index - is a sign that government measures to cool the market, implemented in September 2009 and February 2010, have reined in runaway price increases.
Official data released by URA last week showed that prices of non-landed properties increased 4.9 per cent in Q1, down from 7.2 per cent in the preceding quarter.
URA's index also showed that prices in the 'core central region', which roughly correlates to the central region classification used by the NUS index, rose 4.4 per cent in Q1 - faster than home prices in the 'outside central region', which rose 4.3 per cent.
URA's index showed that prices in the mid-level 'rest of central region' rose 7.9 per cent in Q1.
The numbers from URA and NUS differ because the two indices use different methods to track prices.
NUS's index, which is compiled by the Institute of Real Estate Studies, was launched in March to serve as a resource for developing property derivatives in Singapore.
It is computed using the market values of a basket of completed properties. Uncompleted projects are not included in the basket as price movements for such projects can be different from those in the rest of the market.
But the impact of new launches on the prices of completed properties in the vicinity is factored in.
The URA index, on the other hand, includes transactions at new launches and sub-sales. The differences mean that the two indices can throw up different numbers, market watchers have said.
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.

Slowing down: Analysts say that the moderation in the growth of prices is a sign that government measures to cool the market have reined in runaway price increases
Non-central home prices outpace prime areas
NUS index shows they climbed 1.2% in March while central region home prices dipped
By UMA SHANKARI
(SINGAPORE) Prices of non-landed private homes outside Singapore's prime districts are now growing at a faster rate than prices in the prime districts, according to a new index compiled by the National University of Singapore (NUS).
Flash estimates for March released yesterday show that 'non-central' home prices climbed 1.2 per cent last month, taking the first-quarter rise to 4.4 per cent.
In contrast, prices in the central region - postal districts 1-4 and 9-11 - dipped 0.07 per cent in March. For Q1, they rose 1.7 per cent.
NUS's Singapore Residential Price Index also shows that overall home prices rose 0.3 per cent last month and 2.8 per cent in Q1.
This puts the overall current value of the index just 0.1 per cent below the peak in November 2007. Prices in the central region are now 9.3 per cent below that peak, while prices in non-central areas are 6.4 per cent above the previous peak in January 2008.
'The rate of price growth in the central area has slowed, but for the non-central region, we have not seen an obvious decline in the rate of growth yet,' said Associate Professor Lum Sau Kim, who leads the group that compiles the index.
In 2009, price growth in the central region outpaced that in non-central areas. Home prices grew 27.3 per cent in the central region and 19.5 per cent in non-central areas. The overall index rose 22.2 per cent.
Analysts say that the moderation in the growth of prices - seen in both the NUS index and official Urban Redevelopment Authority index - is a sign that government measures to cool the market, implemented in September 2009 and February 2010, have reined in runaway price increases.
Official data released by URA last week showed that prices of non-landed properties increased 4.9 per cent in Q1, down from 7.2 per cent in the preceding quarter.
URA's index also showed that prices in the 'core central region', which roughly correlates to the central region classification used by the NUS index, rose 4.4 per cent in Q1 - faster than home prices in the 'outside central region', which rose 4.3 per cent.
URA's index showed that prices in the mid-level 'rest of central region' rose 7.9 per cent in Q1.
The numbers from URA and NUS differ because the two indices use different methods to track prices.
NUS's index, which is compiled by the Institute of Real Estate Studies, was launched in March to serve as a resource for developing property derivatives in Singapore.
It is computed using the market values of a basket of completed properties. Uncompleted projects are not included in the basket as price movements for such projects can be different from those in the rest of the market.
But the impact of new launches on the prices of completed properties in the vicinity is factored in.
The URA index, on the other hand, includes transactions at new launches and sub-sales. The differences mean that the two indices can throw up different numbers, market watchers have said.
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.

Slowing down: Analysts say that the moderation in the growth of prices is a sign that government measures to cool the market have reined in runaway price increases
BT : China suspends capital raising by property firms
Business Times - 29 Apr 2010
China suspends capital raising by property firms
Moratorium may block 110b yuan in share issues planned by 45 companies
(BEIJING) China will place a moratorium on capital raising by real estate firms as part of a broader campaign to rein in property price rises, state media reported yesterday.
The move could stand in the way of about 110 billion yuan (S$22 billion) in share issues planned by 45 companies, unnamed sources close to the China Securities Regulatory Commission told the China Daily.
The suspension will allow the authorities to examine whether companies have used illegal methods to manipulate market prices, the newspaper said.
Beijing, wary about the risks of an asset bubble, has been trying to cool the real estate market, raising mortgage rates and down payment requirements for second homes and pushing local governments to control speculative buying.
Those steps complement general efforts to prevent the economy from overheating as it fully regained its momentum with the help of booming credit and grew nearly 11.9 per cent in the first quarter from a year earlier, the fastest since 2007.
China's banking regulator has also issued new guidelines to make it harder for property developers to obtain funding from trust companies, the 21st Century Business Herald quoted an unnamed executive at a trust company as saying.
Real estate firms seeking loans from trust firms must meet the minimum capital requirement and provide proof of their qualifications for developing a project, the newspaper said.
This would represent a clarification and tightening of rules governing the financing relationship between trust firms and property developers. Real estate firms have been turning to trust companies because they have looser capital requirements than banks.
Share prices of Chinese property firms have tumbled over the past week, dragging down the main stock index in Shanghai to its lowest level in more than half a year.
But the formation of a property bubble in China has become one of the major risks to sustainable economic growth, the Development Research Centre, a think-tank under the State Council, said yesterday.
In its report, published in the China Economic Times, it said that steps taken in recent months by the government had not yet succeeded in tamping down on surging property prices.
'If the controls are not forceful, with our country's growth and development clearly outstripping that of other countries, hot money inflows will quicken and excessive domestic liquidity will increase, progressively inflating asset bubbles,' it said. -- Reuters
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.

Towering prices: Beijing, wary about the risks of an asset bubble, has been trying to cool the real estate market, raising mortgage rates and down payment requirements for second homes and pushing local governments to control speculative buying
China suspends capital raising by property firms
Moratorium may block 110b yuan in share issues planned by 45 companies
(BEIJING) China will place a moratorium on capital raising by real estate firms as part of a broader campaign to rein in property price rises, state media reported yesterday.
The move could stand in the way of about 110 billion yuan (S$22 billion) in share issues planned by 45 companies, unnamed sources close to the China Securities Regulatory Commission told the China Daily.
The suspension will allow the authorities to examine whether companies have used illegal methods to manipulate market prices, the newspaper said.
Beijing, wary about the risks of an asset bubble, has been trying to cool the real estate market, raising mortgage rates and down payment requirements for second homes and pushing local governments to control speculative buying.
Those steps complement general efforts to prevent the economy from overheating as it fully regained its momentum with the help of booming credit and grew nearly 11.9 per cent in the first quarter from a year earlier, the fastest since 2007.
China's banking regulator has also issued new guidelines to make it harder for property developers to obtain funding from trust companies, the 21st Century Business Herald quoted an unnamed executive at a trust company as saying.
Real estate firms seeking loans from trust firms must meet the minimum capital requirement and provide proof of their qualifications for developing a project, the newspaper said.
This would represent a clarification and tightening of rules governing the financing relationship between trust firms and property developers. Real estate firms have been turning to trust companies because they have looser capital requirements than banks.
Share prices of Chinese property firms have tumbled over the past week, dragging down the main stock index in Shanghai to its lowest level in more than half a year.
But the formation of a property bubble in China has become one of the major risks to sustainable economic growth, the Development Research Centre, a think-tank under the State Council, said yesterday.
In its report, published in the China Economic Times, it said that steps taken in recent months by the government had not yet succeeded in tamping down on surging property prices.
'If the controls are not forceful, with our country's growth and development clearly outstripping that of other countries, hot money inflows will quicken and excessive domestic liquidity will increase, progressively inflating asset bubbles,' it said. -- Reuters
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.

Towering prices: Beijing, wary about the risks of an asset bubble, has been trying to cool the real estate market, raising mortgage rates and down payment requirements for second homes and pushing local governments to control speculative buying
BT : Sands eyes US$12 billion from sale of Macau assets
Business Times - 29 Apr 2010
Sands eyes US$12 billion from sale of Macau assets
CEO raises Marina Bay Sands forecast, investment to be recouped in 5 years
(SINGAPORE) Las Vegas Sands Corp chairman Sheldon Adelson said that the planned sale of the casino operator's Macau malls and apartments may raise as much as US$12 billion and recoup their construction costs.
'It will be like US$12 billion if we add up all the apartments and all the retail in
Macau,' including those in buildings still under construction, Mr Adelson, the founder and chief executive officer of Las Vegas Sands, said in an interview in Singapore on Tuesday. The company may start selling the Macau assets within 21/2 years, he said.
Sands, which Adelson describes as 'an Asian company with a presence in Las Vegas and the US', gets 73 per cent of its revenue from Macau, the world's largest gambling market. He was in Singapore on Tuesday to open the first phase of Marina Bay Sands, and raised his earnings forecast for the resort, saying that the US$5.5 billion invested in it will be recouped in five years.
Sands' casino resort on Tuesday opened 963 of its 2,560 hotel rooms, the casino, the meeting and convention facilities, parts of its shopping mall and some restaurants. A grand opening party will be held on June 23 when the second phase is unveiled, including a sky park, additional shops and more restaurants.
Asia will contribute 85 per cent of revenue once the Singapore casino 'ramps up', said Mr Adelson. Last year's sales totalled US$4.56 billion, with 27 per cent coming from Las Vegas, where the company is based.
Macau assets that Sands may sell include the Four Seasons apartments and shopping areas in the Venetian Macau casino resort and in the Four Seasons hotel, Mr Adelson said. The plan also includes selling condominiums at the St Regis, where construction is resuming.
'That is our fundamental business model - we get our money back from the sale of non-core business assets,' he said.
Still, Jonathan Galaviz, an independent strategist who follows travel and leisure in Asia, said that apartments and malls in Macau may be a tough sell to investors, given that the city isn't a proven place for housing investment, and that a huge asset bubble may be developing in Asian real estate.
'Second-home buyers in Asia tend to have an affinity for beach and costal destinations, so Macau's proposition will need to be unique in order to compete,' Mr Galaviz said in an e-mail. As for malls, 'the average length of stay for Macau's average tourist - around one night - doesn't yet lend itself to a strong and dynamic retail opportunity'.
Sands fell US$1.51, or 5.8 per cent, to close at US$24.69 on the New York Stock Exchange composite trading on Tuesday. The stock has gained 65 per cent this year.
Mr Adelson, who is Sands' controlling shareholder, said in December that selling the retail areas at the Four Seasons and the Venetian would raise enough money to pay Sands' debt. The company has US$12.2 billion of bonds and loans due from next year to 2015, according to data compiled by Bloomberg.
The billionaire, who previously said that the Singapore project would add more than US$1 billion in annual earnings before interest, tax, depreciation and amortisation, didn't provide a new figure apart from saying that he was raising his forecast. The return period compares with four years for the Macau project, which cost about half as much to build, Mr Adelson said.
The Marina Bay Sands in Singapore will be a 'grand slam home run', Mr Adelson said. 'Asian people just love to gamble.'
Singapore aims to lure 17 million visitors and triple annual tourism revenue to S$30 billion (US$22 billion) by 2015, helped by two casino resorts, Marina Bay Sands and Genting Bhd's Resorts World Sentosa.
The Marina Bay Sands casino, which makes up about 3 per cent of the 15,000 sq m resort, has about 600 table games and more than 1,500 slot machines.
Asia has room for five to 10 cities like Las Vegas, Mr Adelson said. The most likely countries to approve casinos in the region are Japan and Taiwan, he said. -- Bloomberg
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.
Rowing away: Sands may sell the Four Seasons apartments and shopping areas in the Venetian Macau (above) and in the Four Seasons hotel, Mr Adelson says

Sands eyes US$12 billion from sale of Macau assets
CEO raises Marina Bay Sands forecast, investment to be recouped in 5 years
(SINGAPORE) Las Vegas Sands Corp chairman Sheldon Adelson said that the planned sale of the casino operator's Macau malls and apartments may raise as much as US$12 billion and recoup their construction costs.
'It will be like US$12 billion if we add up all the apartments and all the retail in
Macau,' including those in buildings still under construction, Mr Adelson, the founder and chief executive officer of Las Vegas Sands, said in an interview in Singapore on Tuesday. The company may start selling the Macau assets within 21/2 years, he said.
Sands, which Adelson describes as 'an Asian company with a presence in Las Vegas and the US', gets 73 per cent of its revenue from Macau, the world's largest gambling market. He was in Singapore on Tuesday to open the first phase of Marina Bay Sands, and raised his earnings forecast for the resort, saying that the US$5.5 billion invested in it will be recouped in five years.
Sands' casino resort on Tuesday opened 963 of its 2,560 hotel rooms, the casino, the meeting and convention facilities, parts of its shopping mall and some restaurants. A grand opening party will be held on June 23 when the second phase is unveiled, including a sky park, additional shops and more restaurants.
Asia will contribute 85 per cent of revenue once the Singapore casino 'ramps up', said Mr Adelson. Last year's sales totalled US$4.56 billion, with 27 per cent coming from Las Vegas, where the company is based.
Macau assets that Sands may sell include the Four Seasons apartments and shopping areas in the Venetian Macau casino resort and in the Four Seasons hotel, Mr Adelson said. The plan also includes selling condominiums at the St Regis, where construction is resuming.
'That is our fundamental business model - we get our money back from the sale of non-core business assets,' he said.
Still, Jonathan Galaviz, an independent strategist who follows travel and leisure in Asia, said that apartments and malls in Macau may be a tough sell to investors, given that the city isn't a proven place for housing investment, and that a huge asset bubble may be developing in Asian real estate.
'Second-home buyers in Asia tend to have an affinity for beach and costal destinations, so Macau's proposition will need to be unique in order to compete,' Mr Galaviz said in an e-mail. As for malls, 'the average length of stay for Macau's average tourist - around one night - doesn't yet lend itself to a strong and dynamic retail opportunity'.
Sands fell US$1.51, or 5.8 per cent, to close at US$24.69 on the New York Stock Exchange composite trading on Tuesday. The stock has gained 65 per cent this year.
Mr Adelson, who is Sands' controlling shareholder, said in December that selling the retail areas at the Four Seasons and the Venetian would raise enough money to pay Sands' debt. The company has US$12.2 billion of bonds and loans due from next year to 2015, according to data compiled by Bloomberg.
The billionaire, who previously said that the Singapore project would add more than US$1 billion in annual earnings before interest, tax, depreciation and amortisation, didn't provide a new figure apart from saying that he was raising his forecast. The return period compares with four years for the Macau project, which cost about half as much to build, Mr Adelson said.
The Marina Bay Sands in Singapore will be a 'grand slam home run', Mr Adelson said. 'Asian people just love to gamble.'
Singapore aims to lure 17 million visitors and triple annual tourism revenue to S$30 billion (US$22 billion) by 2015, helped by two casino resorts, Marina Bay Sands and Genting Bhd's Resorts World Sentosa.
The Marina Bay Sands casino, which makes up about 3 per cent of the 15,000 sq m resort, has about 600 table games and more than 1,500 slot machines.
Asia has room for five to 10 cities like Las Vegas, Mr Adelson said. The most likely countries to approve casinos in the region are Japan and Taiwan, he said. -- Bloomberg
Copyright © 2010 Singapore Press Holdings Ltd. All rights reserved.
Rowing away: Sands may sell the Four Seasons apartments and shopping areas in the Venetian Macau (above) and in the Four Seasons hotel, Mr Adelson says

Subscribe to:
Posts (Atom)

 Posts


